
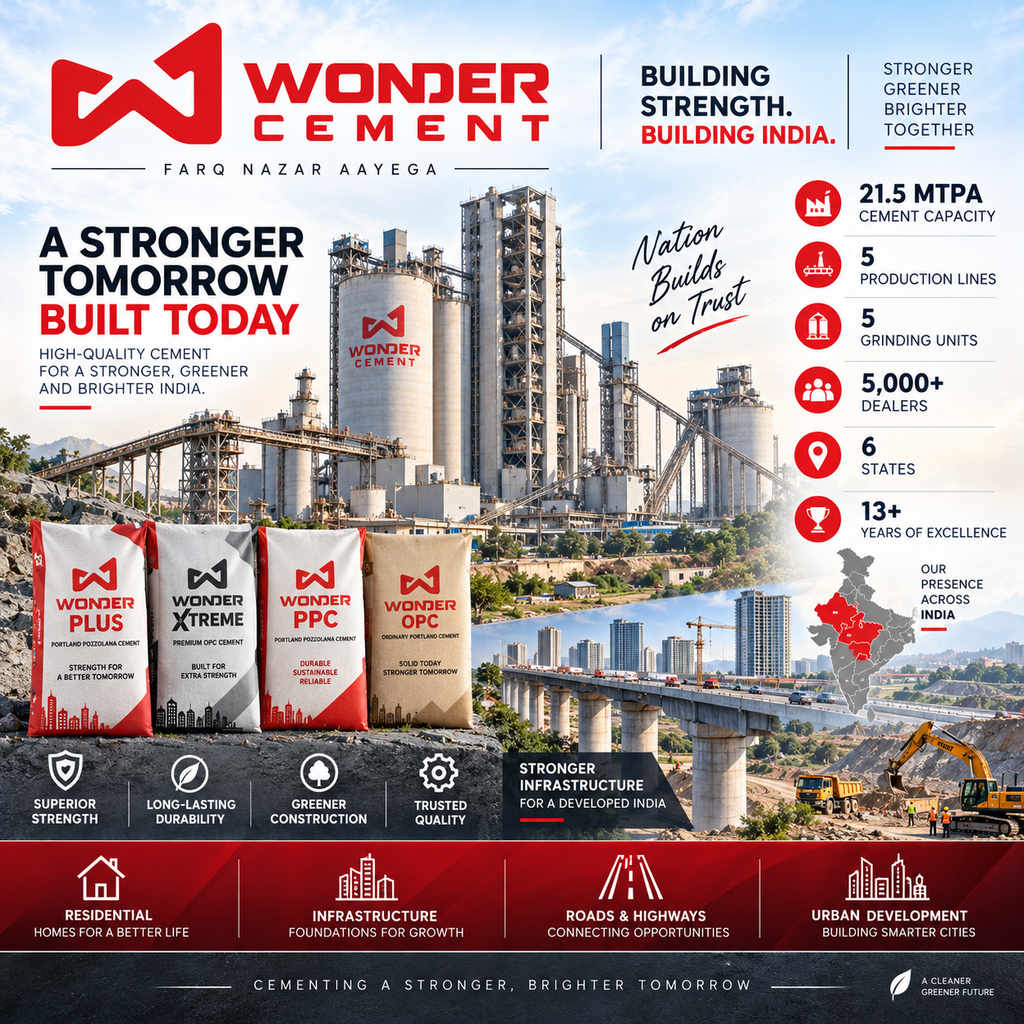
Wonder Cement Limited (WCL) is an unlisted public company and one of India’s prominent cement manufacturers. The company is promoted by the Rajasthan-based R.K. Group, the group associated with R.K. Marble, and operates an integrated cement manufacturing facility at Nimbahera, Rajasthan, supported by five grinding units across western, northern and central India.
Wonder Cement – Official Website
Company Snapshot
| Particular | Details |
|---|---|
| Company | Wonder Cement Limited |
| CIN | U26943RJ2005PLC021205 |
| Incorporated | 26 August 2005 |
| Registered Office | Makrana Road, Madanganj-Kishangarh, Rajasthan |
| Corporate Office | Udaipur, Rajasthan |
| Status | Unlisted Public Company |
| Industry | Cement & Building Materials |
| Promoter Group | R.K. Group / Patni family |
| Paid-up Capital | ~₹536.8 Cr |
| Current Cement Capacity | 21.5 MTPA |
| Current Clinker Capacity | ~13.8 MTPA |
| Main Plant | Nimbahera, Rajasthan |
| Key Markets | Rajasthan, Gujarat, MP, UP, Haryana, Maharashtra, Delhi NCR & North India |
MCA-linked company databases report Wonder Cement as an active, unlisted public company with paid-up capital of approximately ₹536.8 Cr.
Business Overview
Wonder Cement manufactures and sells cement primarily under the Wonder brand.
Its product portfolio includes:
- Wonder OPC
- Wonder PPC
- Wonder Plus
- Wonder Xtreme
- Specialty cement products
The company serves both retail/trade customers and institutional/non-trade customers.
Its cement is used across residential construction, commercial buildings and large infrastructure projects.
The company’s website highlights usage in projects including the Dedicated Freight Corridor, Mumbai Coastal Road, Barmer Refinery, Gujarat Bullet Train Project, Delhi Central Vista and Jewar International Airport.
Manufacturing Footprint
Wonder Cement’s manufacturing network has expanded significantly over the last decade.
Nimbahera Integrated Plant – Rajasthan
Nimbahera remains the company’s core manufacturing hub.
The company started production in 2012 and subsequently added production lines in 2015, 2019, 2022 and 2025. The fifth production line was commissioned in 2025.
Grinding Units
Wonder Cement currently operates five grinding units:
| Location | State | Capacity |
|---|---|---|
| Dhule | Maharashtra | 2 MTPA |
| Badnawar | Madhya Pradesh | 2 MTPA |
| Jhajjar | Haryana | 3 MTPA |
| Aligarh | Uttar Pradesh | 2 MTPA |
| Tulsigam | Gujarat | 2 MTPA |
Together with Nimbahera, the company currently states total cement capacity of 21.5 MTPA.
Capacity Expansion
Expansion remains a major part of the Wonder Cement growth strategy.
CARE Ratings reported that the company plans approximately ₹5,193 Cr of capex between FY26 and FY28.
The planned projects include:
Jaisalmer Integrated Unit
- 3.3 MTPA clinker
- 2.5 MTPA grinding capacity
Suratgarh Grinding Unit
- 2.5 MTPA grinding capacity
Renewable Energy
- 107 MW AC solar project
- ~160.5 MW DC capacity
- Battery storage of more than 100 MWh
Other Expansion
- Limestone mine acquisition in Central India
- Efficiency and maintenance projects
CARE estimates the capex will be funded through a debt-to-equity ratio of approximately 1.42:1.
Financial Performance
FY23–FY25
| ₹ Crore | FY23 | FY24 | FY25 |
|---|---|---|---|
| Operating Income | — | 7,095 | 7,380 |
| PBILDT | — | 1,381 | 1,515 |
| PAT | — | 466 | 505 |
| Net Worth | — | 2,619 | 3,110 |
| Overall Gearing | — | 1.07x | 0.87x |
| Interest Coverage | — | 6.13x | 6.16x |
CARE Ratings reported FY25 operating income of ₹7,380 Cr, PBILDT of ₹1,515 Cr and PAT of ₹505 Cr.
Business Standard’s unlisted-company database also reported FY25 revenue of approximately ₹7,547 Cr and PAT of approximately ₹443 Cr; the difference reflects different reporting bases and financial-data methodologies, so the CARE figures are used as the primary credit-analysis reference here.
H1 FY26 Performance
The company continued to grow during the first half of FY26.
| Metric | H1 FY25 | H1 FY26 |
|---|---|---|
| Operating Income | — | ₹3,729 Cr |
| PBILDT | ₹804 Cr | ₹790 Cr |
| PAT | — | ₹343 Cr |
| PBILDT Margin | — | 21.18% |
| Interest Coverage | — | 6.90x |
CARE reported H1 FY26 operating income of ₹3,729 Cr, up approximately 7.76% YoY, while PBILDT margin improved to 21.18%.
Operating Efficiency
One of Wonder Cement’s structural advantages is its access to captive resources.
The company has:
- More than 699 MMT of captive limestone reserves
- Captive thermal power
- Waste heat recovery
- Wind power
- Solar power
- Total captive power capacity of approximately 143.67 MW as reported by CARE in September 2025
Captive power supplied approximately 51% of total power requirements in FY25 and H1 FY26.
Power consumption also improved from 70.11 KWh/tonne in FY21 to 63.40 KWh/tonne in FY25, supporting cost efficiency.
Market Presence
Wonder Cement has gradually diversified beyond its traditional Rajasthan market.
FY25 Sales Mix by Geography
| Market | Approx. Contribution |
|---|---|
| Rajasthan | 26% |
| Gujarat | 19% |
| Madhya Pradesh | 16% |
| Uttar Pradesh | 12% |
| Haryana | 11% |
Overall, CARE estimates FY25 sales exposure at approximately:
- North – 45%
- West – 29%
- Central – 28%
The reduction in Rajasthan’s contribution from around 40% in FY19 to 26% in FY25 demonstrates the company’s geographic diversification.
Distribution Network
Wonder Cement has built a substantial dealer and distribution network across its core markets.
The company currently states that it has 5,000+ trusted dealers across India.
Its key markets include:
- Rajasthan
- Gujarat
- Madhya Pradesh
- Uttar Pradesh
- Haryana
- Maharashtra
- Delhi NCR
- Punjab
- Uttarakhand
- Himachal Pradesh
- Jammu & Kashmir
Credit Rating
Wonder Cement has a strong credit profile.
CARE Ratings
CARE AA; Stable – Long Term
CARE AA; Stable / CARE A1+ – Long/Short Term
In December 2025, CARE reaffirmed the ratings on bank facilities and increased the rated long-term bank facilities to approximately ₹6,119.66 Cr, with additional long/short-term facilities of ₹1,600 Cr.
The rating agency highlighted:
- Strong brand presence
- Increasing scale
- Growing capacity
- Established dealer network
- Captive limestone reserves
- Captive power
- Experienced promoters
- Professional management
- Healthy operating margins
Promoter & Management
Wonder Cement is promoted by the R.K. Group / Patni family.
The company traces its business heritage to R.K. Marble, which has operated in the marble industry for decades. Wonder Cement was subsequently established as the group’s cement manufacturing business.
Key leadership includes members of the Patni family along with professional management. Company records identify individuals including Ashok Patni, Suresh Patni, Vimal Patni and Vivek Patni, while Kiran Dattatrayrao Patil is identified as Managing Director in company databases.
Sustainability & Renewable Energy
Wonder Cement has been investing in renewable energy and efficiency initiatives.
Its sustainability framework focuses on:
- Decarbonisation
- Energy efficiency
- Resource circularity
- Water stewardship
- Biodiversity
- Workplace safety
- Governance
The planned 107 MW AC solar project with battery storage is another significant step in reducing dependence on conventional power sources.
Key Growth Drivers
1. Capacity Expansion
The company is moving from a regional cement manufacturer toward a larger multi-region player, supported by the 21.5 MTPA current cement capacity and additional projects planned through FY28.
2. Infrastructure Spending
Higher government and private infrastructure spending can support cement demand.
3. Geographic Expansion
Increasing presence in Gujarat, Madhya Pradesh, Uttar Pradesh and other markets reduces dependence on Rajasthan.
4. Captive Limestone
Large captive limestone reserves provide a structural raw-material advantage.
5. Cost Efficiency
Captive power, WHRS, renewable energy and integrated manufacturing can help control production costs.
Key Risks
Cement Industry Cyclicality
Cement prices and profitability are sensitive to regional supply-demand conditions, infrastructure activity and construction cycles.
Large Capex Requirement
Approximately ₹5,193 Cr of planned FY26–FY28 capex creates execution and funding requirements.
Leverage
CARE expects leverage to rise as debt is used to fund expansion. Net debt/PBILDT could reach around 2.5x during FY27 before improving as new projects generate cash flows.
Clinker Concentration
While grinding capacity is spread across multiple states, clinker production has historically been concentrated at Nimbahera. The Jaisalmer project is intended to partially reduce this concentration.
Input Costs
Coal, petcoke, gypsum, fly ash, power and freight costs can materially influence cement margins.
Cement Price Realisation
Cement is a competitive commodity business. Weak regional pricing can offset volume growth.
Subsidy Receivables
CARE reported approximately ₹433 Cr of outstanding state subsidy receivables as of March 2025, rising to ₹475 Cr as of September 2025, making timely receipt of these amounts a monitorable.
IPO Status
Wonder Cement remains an unlisted public company. I could not verify a current SEBI DRHP for a Wonder Cement IPO as of September 2026 from the sources reviewed.
Therefore, an IPO date, issue size or expected listing valuation should not be assumed without a formal filing.
Unlisted Share Valuation
Because Wonder Cement is not listed on NSE/BSE, there is no continuously traded market price comparable to listed cement companies.
For an unlisted investor, valuation should primarily be assessed using:
- FY25/FY26 earnings
- Replacement value of cement capacity
- EV/EBITDA compared with listed cement peers
- Net debt
- Upcoming capacity additions
- Promoter/group structure
- Cash generation
- Potential future liquidity/IPO event
Any private-market transaction price should therefore be treated as indicative rather than an exchange-discovered price.
Investment Checklist
| Factor | Observation |
|---|---|
| Business | Cement manufacturing |
| Promoter | R.K. Group / Patni family |
| Current Cement Capacity | 21.5 MTPA |
| Clinker Capacity | ~13.8 MTPA |
| FY25 Revenue | ~₹7,380 Cr |
| FY25 PAT | ~₹505 Cr |
| FY25 Net Worth | ~₹3,110 Cr |
| H1 FY26 Revenue | ₹3,729 Cr |
| H1 FY26 PAT | ₹343 Cr |
| Credit Rating | CARE AA; Stable |
| Planned FY26–28 Capex | ~₹5,193 Cr |
| Captive Limestone | 699+ MMT |
| Listed | No |
| IPO | No verified current DRHP found |
UnlistedCart Takeaway
Wonder Cement is a large, established unlisted cement manufacturer backed by the R.K. Group, with 21.5 MTPA of current cement capacity, strong brand presence, captive limestone resources and a significant expansion programme.
The key numbers to track are ₹7,380 Cr FY25 operating income, ₹505 Cr FY25 PAT, ₹3,110 Cr net worth, 21.5 MTPA cement capacity and ~₹5,193 Cr planned FY26–FY28 capex.
The key investment debate is likely to revolve around how much value is assigned to the company’s expansion capacity versus the additional debt required to fund it. Execution of the Jaisalmer and Suratgarh projects, cement price realisations, energy costs and regional capacity utilisation will be important variables over the next few years.
Important: Wonder Cement is unlisted. Private-market share prices can differ materially between transactions because of liquidity, seller availability, transaction size and valuation expectations. Investors should verify the latest audited financial statements, shareholding, transaction price and transferability before any transaction.
Useful Links
Wonder Cement – Official Website
Wonder Cement – Company Profile
Wonder Cement – Manufacturing Plants
Wonder Cement – Annual Returns
Wonder Cement – Sustainability
CARE Ratings – Wonder Cement Rating Rationale
For more such unlisted stocks visit UnlistedCart – Unlisted Shares
