
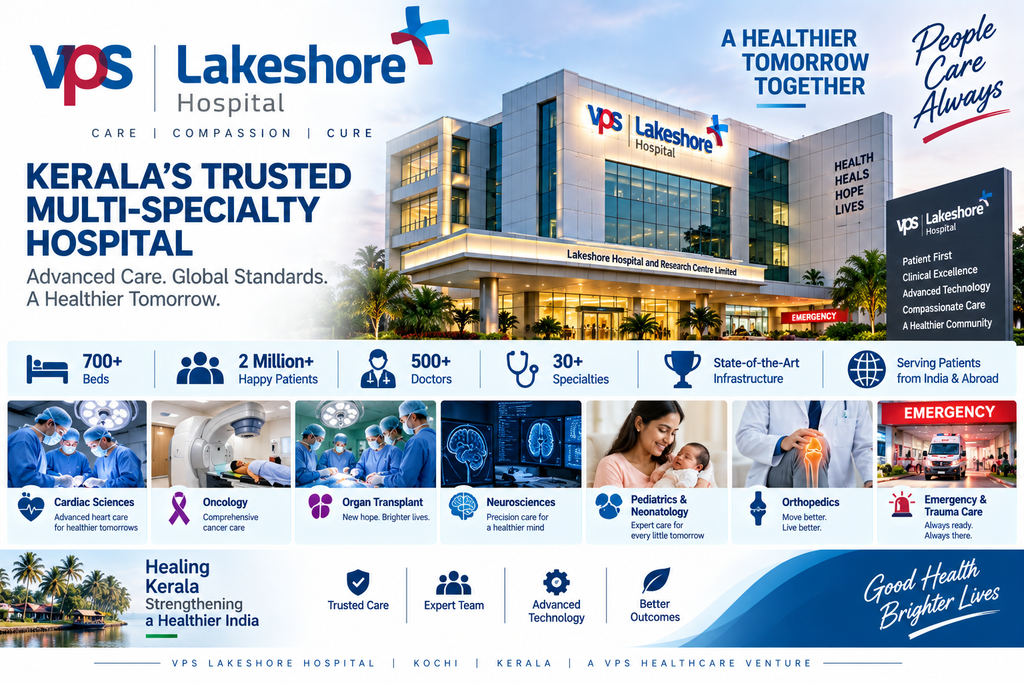
VPS Lakeshore Hospital | Unlisted Share Research Report | FY2026
Sector: Healthcare / Hospitals
Company: Lakeshore Hospital and Research Centre Limited
Brand: VPS Lakeshore Hospital
CIN: U85110KL1996PLC010260
ISIN: INE01TI01010
Face Value: ₹10 per share
Registered Office: Maradu, Nettoor, Kochi, Kerala
Status: Unlisted Public Limited Company
1. Company Overview
Lakeshore Hospital and Research Centre Limited operates VPS Lakeshore Hospital, a multi-specialty tertiary-care hospital in Kochi, Kerala.
The company was incorporated on 4 April 1996 and operates a super-specialty hospital providing advanced medical and surgical care. Its official investor information confirms paid-up capital of ₹100 Cr, represented by 10 crore equity shares of ₹10 each.
The hospital has developed a strong presence in complex and specialty healthcare, including oncology, cardiac sciences, organ transplantation, gastroenterology, neurosciences, orthopedics and critical care.
VPS Lakeshore Hospital – Official Website
2. Business Model
Lakeshore follows the conventional tertiary-care hospital model:
Patients → Diagnostics & Consultation → Procedures / Surgery → In-patient & Out-patient Care → Follow-up
Revenue is generated primarily through:
- In-patient treatment
- Out-patient consultations
- Surgeries and procedures
- Critical care
- Diagnostics
- Pharmacy and consumables
- Organ transplantation
- Oncology
- Cardiac care
- Gastroenterology
- Neurosciences
- Orthopedics and trauma care
The company’s FY25 annual report states that its principal business activity is hospital activities, with hospital services representing 100% of turnover.
3. Key Specialties
VPS Lakeshore’s official website highlights several high-value medical specialties:
| Specialty | Key Capabilities |
|---|---|
| Oncology | Medical & pediatric oncology, surgical oncology |
| Cardiac Sciences | Cardiology, cardiac surgery, heart transplant, ECMO |
| Nephrology | Kidney care and kidney transplantation |
| Gastroenterology | Medical & surgical gastroenterology, HPB surgery |
| Liver Care | Comprehensive liver care and liver transplantation |
| Neurosciences | Neurosurgery and neurological care |
| Orthopedics | Joint replacement, trauma and sports medicine |
| Pediatrics | Pediatrics & neonatology |
| Plastic Surgery | Plastic & reconstructive surgery |
| Emergency Care | Trauma Action Team |
| Stroke Care | Rapid Six stroke-management programme |
4. Why Specialised Healthcare Matters
The hospital business is increasingly moving toward higher-acuity and complex procedures, where revenue per patient can be significantly higher than routine outpatient care.
Lakeshore’s exposure to:
Cancer care + transplants + cardiac sciences + neurosurgery + critical care
gives it exposure to complex healthcare services where specialised infrastructure and clinical expertise can create barriers to entry.
5. FY2026 Financial Performance
FY26 was a strong year operationally.
| ₹ Crore | FY25 | FY26 | YoY |
|---|---|---|---|
| Revenue from Operations | 407.52 | 452.74 | +11.1% |
| Other Income | 8.23 | 8.45 | +2.7% |
| Total Income | 415.75 | 461.18 | +10.9% |
| PBT | 52.73 | 71.41 | +35.4% |
| PAT | 39.12 | 53.06 | +35.6% |
| EPS | ₹3.91 | ₹5.31 | +35.8% |
Key takeaway
Revenue grew around 11%, but PAT grew by more than 35%.
This indicates meaningful operating leverage and improved profitability.
The company’s FY26 EBITDA was reported at approximately ₹90.7 Cr, implying an EBITDA margin of roughly 20%, compared with around 17.5% in FY25.
6. Profitability Trend
The recent trend is worth tracking:
| ₹ Cr | FY23 | FY24 | FY25 | FY26 |
|---|---|---|---|---|
| Revenue | 419 | 396 | 408 | 453 |
| EBITDA | 102 | 73 | 71 | 91 |
| PBT | 82 | 55 | 53 | 71 |
| PAT | 57 | 44 | 39 | 53 |
FY24 and FY25 saw weaker profitability, while FY26 shows a clear recovery.
FY26 margin improvement
FY25 EBITDA margin: ~17.5%
FY26 EBITDA margin: ~20.0%
The company therefore appears to have recovered a meaningful portion of its earlier operating margin.
7. Cash Flow
Operating cash generation remained healthy.
FY26:
Operating Cash Flow: ₹56.5 Cr
versus:
FY25: ₹60.1 Cr
Despite higher PBT, operating cash flow declined slightly because working-capital movements and higher tax payments absorbed cash.
The company invested approximately:
₹35.5 Cr
in property, plant and equipment and capital work-in-progress during FY26.
This suggests the hospital continues to reinvest in its infrastructure.
8. Balance Sheet
FY26 consolidated assets stood at approximately:
₹553.2 Cr
compared with ₹533.3 Cr in FY25.
| Particulars | FY26 |
|---|---|
| Total Assets | ₹553.2 Cr |
| Equity | ₹455.7 Cr |
| PPE | ₹354.1 Cr |
| Cash & Cash Equivalents | ₹45.6 Cr |
| Other Bank Balances | ₹40.6 Cr |
| Trade Receivables | ₹56.8 Cr |
| Debt/Lease Liabilities | Very low |
The company has a particularly strong balance sheet relative to its earnings.
9. Debt Position
The debt-equity ratio was approximately:
0.01x
for both FY25 and FY26.
This is a notable characteristic of Lakeshore.
Unlike many hospital chains that rely heavily on debt to fund new hospitals and expansion, Lakeshore currently has very low financial leverage.
That can provide flexibility for:
- Capacity expansion
- New medical equipment
- Specialty centres
- Technology upgrades
- Renovation
- Future hospital projects
10. Current Ratio
FY26 current ratio:
2.58x
versus 2.25x in FY25.
This indicates a relatively comfortable short-term liquidity position.
11. Shareholding
The official company disclosure provides the following 31 March 2026 ownership categories:
| Category | Holding |
|---|---|
| Directors | 51.13% |
| Directors’ Relatives | 19.85% |
| Employees | 1.43% |
| Resident Members | 14.34% |
| Non-Resident Members | 12.46% |
| Body Corporates / LLPs | 0.79% |
Therefore, directors and their relatives collectively controlled approximately:
70.98%
of the company as of 31 March 2026.
Some unlisted-market databases attribute major individual holdings to Dr. V. P. Shamsheer and M. A. Yusuff Ali, but the company’s official disclosure above reports holdings by category rather than providing the same named-holder breakdown.
12. Management
The company’s official website identifies:
Dr. V. P. Shamsheer
Chairman
S. K. Abdulla
Managing Director
The board also includes directors and independent directors with experience across healthcare and corporate functions.
13. Healthcare Infrastructure
Lakeshore has developed a tertiary-care ecosystem around Kochi, with capabilities covering both routine and complex medical procedures.
The hospital’s infrastructure supports:
Cardiac Sciences
Transplantation
Oncology
Neurosurgery
Gastroenterology
Critical Care
Orthopedics
Emergency Medicine
Diagnostics
Pediatrics
The combination of multiple high-acuity specialties is important because complex procedures can generate higher revenue per occupied bed and support premium realisation.
14. Occupancy & Operating Leverage
An internal FY26/FY27 strategic dashboard published for Lakeshore indicates FY26 estimated occupancy of approximately 53%, with FY27 base-case assumptions around 62%. It also estimates FY26 revenue of approximately ₹452.8 Cr and EBITDA of ₹98.8 Cr.
Important: These FY27 figures are management/strategic planning assumptions rather than audited results and should not be treated as actual financial performance.
The implication is that occupancy improvement represents an important potential operating lever because hospital infrastructure costs are relatively fixed.
15. FY27 Potential Operating Drivers
The strategic dashboard identifies several areas that could support further growth:
- Higher bed occupancy
- Growth in oncology
- More complex-care cases
- Higher average revenue per occupied bed
- Referral networks
- Telemedicine and outreach
- Infrastructure transformation
- Better cost utilisation
The dashboard’s FY27 base case assumes revenue of approximately ₹525.7 Cr and EBITDA of ₹107.2 Cr, but these are projections rather than reported results.
16. Current Unlisted Share Price
Lakeshore is not listed on NSE or BSE.
Current private-market references differ:
| Source | Indicative Price |
|---|---|
| UnlistedZone – 11 Sep 2026 | ₹98 |
| BuyUnlistedShares – 13 Sep 2026 | ₹98 |
| WWIPL – current reference | ₹105 |
Therefore, a reasonable current indicative OTC range is approximately:
₹98–₹105 per share
These are private-market reference prices, not exchange-traded quotations.
17. Indicative Valuation
With 10 crore shares outstanding:
At ₹98/share
Implied market capitalisation ≈ ₹980 Cr
At ₹105/share
Implied market capitalisation ≈ ₹1,050 Cr
Using FY26 EPS of ₹5.31:
| Valuation | Approx. |
|---|---|
| P/E at ₹98 | 18.5x |
| P/E at ₹105 | 19.8x |
| Book Value/Share | ~₹46.6 |
| P/B at ₹98 | ~2.1x |
| P/B at ₹105 | ~2.25x |
This places Lakeshore at roughly 18–20x FY26 earnings based on the current indicative private-market range.
18. IPO / Listing Status
There is currently no DRHP filed according to available unlisted-market databases.
Therefore:
IPO: No confirmed IPO
DRHP: Not filed
Price Band: Not available
Listing Date: Not announced
Investors should not purchase the shares solely on an assumption of an imminent IPO.
19. Growth Drivers
1. Healthcare Demand
India’s growing middle class, increasing insurance penetration and rising healthcare awareness support long-term demand for organised tertiary care.
2. Complex Healthcare
Lakeshore’s exposure to oncology, transplantation, cardiac care and neurosurgery provides access to higher-value procedures.
3. Occupancy Improvement
Higher occupancy can increase revenue without requiring proportional increases in fixed infrastructure costs.
4. Higher Case Mix
Greater contribution from complex oncology, transplant and cardiac procedures could increase average revenue per occupied bed.
5. Strong Balance Sheet
Very low leverage gives the company flexibility to fund expansion without taking on excessive debt.
6. Kochi / Kerala Healthcare Market
Lakeshore benefits from its established presence in Kerala and its ability to serve patients from across the region and international markets.
7. Infrastructure Investment
FY26 capex of approximately ₹35.5 Cr demonstrates continued investment in hospital infrastructure.
20. Key Risks
Occupancy Risk
Hospital economics depend heavily on occupancy and utilisation. Under-utilised capacity can pressure margins.
Doctor Dependence
Specialist hospitals depend on highly skilled doctors and consultants. Retention and availability of key clinicians are important.
Regulatory Risk
Healthcare businesses face regulation covering pricing, quality, licensing, medical standards, insurance and patient safety.
Competition
Lakeshore competes with established hospital groups and specialty centres across Kerala and South India.
Capex Risk
Expansion and medical-equipment upgrades require continuous capital expenditure.
Working Capital
FY26 trade receivables increased to approximately ₹56.8 Cr from ₹33.9 Cr, which contributed to weaker cash conversion.
Unlisted Liquidity
The shares are not exchange traded, so liquidity and price discovery can be significantly lower than listed hospital companies.
Valuation Risk
At roughly ₹980–1,050 Cr implied market value, the shares are already valued at around 18–20x FY26 earnings.
21. Comparison With Listed Hospital Model
Lakeshore should broadly be analysed using hospital-industry metrics rather than conventional manufacturing-company metrics.
Investors should track:
Revenue per occupied bed (ARPOB)
Occupancy
EBITDA margin
Revenue growth
Number of beds
Case mix
Doctor fees as % of revenue
Capex per bed
ROCE
Net debt / EBITDA
These metrics provide more insight than P/E alone.
22. What Investors Should Track
For FY27 and beyond, the most important indicators are:
- Revenue growth
- Occupancy rate
- ARPOB
- EBITDA margin
- PAT growth
- Operating cash flow
- Receivable days
- New bed capacity
- Oncology/transplant/cardiac mix
- Capex
- Debt
- Any IPO / strategic transaction development
23. UnlistedCart Takeaway
Lakeshore Hospital is a profitable, low-debt tertiary-care hospital platform with a strong specialty-care franchise in Kerala.
FY26 was particularly encouraging from an operating perspective:
Revenue: ₹452.7 Cr
Revenue growth: ~11%
EBITDA: ~₹90.7 Cr
EBITDA margin: ~20%
PBT: ₹71.4 Cr
PAT: ₹53.1 Cr
PAT growth: ~36%
Debt/Equity: ~0.01x.
At an indicative unlisted price of ₹98–₹105, the implied market capitalisation is approximately ₹980–1,050 Cr, translating to roughly 18–20x FY26 earnings.
The key future variables are occupancy, revenue per occupied bed, high-acuity case mix, EBITDA margin and capacity expansion.
Unlike many highly leveraged hospital businesses, Lakeshore currently has a very conservative balance sheet. The main question for investors is therefore less about debt servicing and more about how efficiently the company can utilise its existing infrastructure and sustain earnings growth.
Important Sources
VPS Lakeshore Hospital – Official Website
VPS Lakeshore – Company & Investor Information
Lakeshore Hospital – FY2024-25 Annual Report
Lakeshore Hospital – Financials
Lakeshore Hospital – Indicative Unlisted Price
Disclaimer: This report is for educational and informational purposes only and should not be considered investment advice, a recommendation, or an offer to buy or sell securities. Unlisted-share prices are indicative OTC references and may vary based on liquidity, transaction size and availability. IPO/listing-related information is subject to change. Investors should independently verify the latest annual report, shareholding, valuation and transaction terms before investing.
For more such unlisted stocks visit UnlistedCart – Unlisted Shares
