
Equity Research Report
Company: Insolation Energy Limited
Brand: INA Solar
Ticker: NSE – INA | BSE – 543620
Industry: Solar PV Manufacturing & Renewable Energy
Report Date: September 2026
Status: Listed – NSE & BSE Main Board
Face Value: ₹1 per Equity Share
Headquarters: Jaipur, Rajasthan
Company Overview
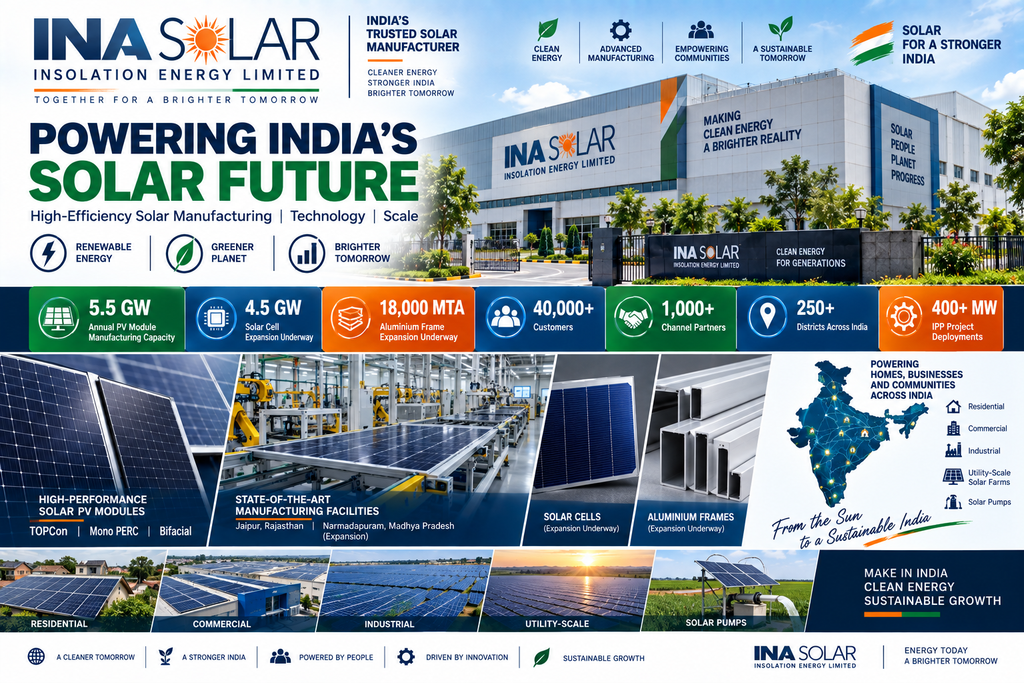
Insolation Energy Limited, operating under the brand INA Solar, is an Indian solar-energy company focused primarily on solar photovoltaic module manufacturing, solar EPC and renewable-energy solutions.
The company began its solar manufacturing journey in 2017 with an initial capacity of 80 MW. It subsequently expanded manufacturing capacity significantly and today reports 5.5 GW of annual solar-module manufacturing capacity.
The company has also begun expanding upstream into solar-cell manufacturing and aluminium-frame manufacturing, with planned capacities of 4.5 GW and 18,000 metric tonnes per annum respectively.
Insolation Energy / INA Solar – Official Website
Listing Status
Insolation Energy was previously listed on the BSE SME platform.
In March 2026, the company migrated to the BSE Main Board and obtained a direct listing on the NSE Capital Market segment.
The company reported that 220,394,625 equity shares of ₹1 face value were listed and made available for trading from March 9, 2026.
Therefore, unlike several of the companies in this report series, Insolation Energy should now be analysed as a listed stock rather than an unlisted share.
Business Model
INA Solar operates across several parts of the solar value chain.
Solar PV Module Manufacturing
The company’s principal business is manufacturing solar PV modules.
Its current portfolio includes:
- TOPCon modules
- Mono PERC modules
- Bifacial modules
- Monofacial modules
- DCR modules
- Non-DCR modules
The company currently manufactures modules ranging from approximately 500 Wp to 635 Wp.
Solar EPC
Through its subsidiaries, the company executes solar EPC projects.
Its EPC exposure includes:
- Utility-scale solar
- Rooftop solar
- Solar parks
- PM-KUSUM projects
- IPP projects
- Government projects
The company’s FY25 Annual Report identifies Insolation Green Infra Private Limited as its EPC subsidiary.
Solar Project Development
The company has executed and participated in multiple solar projects across residential, commercial, industrial and utility-scale applications.
INA Solar states that it has delivered more than 400 MW of IPP projects and serves more than 40,000 customers through a network of more than 1,000 channel partners.
Manufacturing Capacity
The company’s manufacturing expansion has been one of the central drivers of its growth.
| Manufacturing Area | Current / Planned Capacity |
|---|---|
| Solar PV Modules | 5.5 GW |
| Solar Cells | 4.5 GW planned |
| Aluminium Frames | 18,000 MTA planned |
The company currently operates three manufacturing facilities in Jaipur with combined annual module capacity of 5.5 GW.
A fourth facility at Narmadapuram, Madhya Pradesh is being developed for solar-cell and aluminium-frame manufacturing.
Backward Integration Strategy
One of the most important elements of the company’s strategy is vertical integration.
Historically, the company was primarily a solar-module manufacturer.
The next stage is to add:
Solar Cells → Modules → Aluminium Frames → EPC / Project Execution
The objective is to increase control over:
- Component sourcing
- Manufacturing costs
- Product quality
- Supply chain
- Delivery schedules
- Gross margins
The company says the Narmadapuram facility will include 4.5 GW solar-cell manufacturing and 18,000 MTA aluminium-frame manufacturing capacity.
Product Portfolio
INA Solar’s current module portfolio includes:
Diamond Series
- 500 Wp bifacial
- 500 Wp monofacial
- 520–550 Wp bifacial
- 520–550 Wp monofacial
Platinum Series
- 580–600 Wp
- 615–635 Wp G12R
The company is increasingly focused on high-efficiency N-type TOPCon technology.
FY2024-25 Financial Performance
FY25 represented a significant step-up in scale.
Consolidated Performance
₹ Crore
| Particular | FY24 | FY25 | YoY Growth |
|---|---|---|---|
| Revenue / Turnover | 737.17 | 1,333.76 | ~80.9% |
| EBITDA | ~84.2 | 170.32 | ~102.4% |
| PAT | 55.47 | 126.19 | ~127.5% |
| EPS | ₹2.66 | ₹5.95 | ~123.7% |
The company’s FY25 results showed substantial growth in both revenue and profitability.
FY2025-26 Financial Performance
FY26 saw another major increase in scale.
The company reported consolidated turnover of ₹2,163.52 crore, compared with ₹1,343.62 crore in FY25, representing approximately 61.0% growth.
EBITDA increased from ₹172.58 crore to ₹304.62 crore, while PAT increased from ₹125.81 crore to ₹200.47 crore.
FY26 Consolidated Performance
₹ Crore
| Particular | FY25 | FY26 | Growth |
|---|---|---|---|
| Revenue / Turnover | 1,343.62 | 2,163.52 | 61.0% |
| EBITDA | 172.58 | 304.62 | 76.5% |
| PBT | 153.06 | 245.29 | 60.3% |
| PAT | 125.81 | 200.47 | 59.3% |
The combination of revenue growth and stronger EBITDA growth indicates operating leverage during FY26.
Q1 FY2026-27 Performance
The company continued its growth momentum into FY27.
For the quarter ended June 30, 2026, consolidated results were:
| Particular | Q1 FY27 |
|---|---|
| Revenue | ₹745.40 Cr |
| EBITDA | ₹76.87 Cr |
| PBT | ₹47.50 Cr |
| PAT | ₹38.02 Cr |
| EPS | ₹1.73 |
The company reported these results on August 13, 2026.
The Q1 FY27 numbers indicate that the company’s scale-up continued into the new financial year.
FY26 to Q1 FY27 Earnings
The FY26 PAT of ₹200.47 crore and Q1 FY27 PAT of ₹38.02 crore provide a useful starting point for assessing earnings momentum.
However, investors should avoid simply annualising one quarter because solar-module margins can vary with:
- Module prices
- Silicon / wafer prices
- Product mix
- Capacity utilisation
- Inventory valuation
- Import prices
- Competitive intensity
Order Book
As of Q3 FY26, the company reported an order book of approximately 2.1 GW.
This provided demand visibility for the company’s manufacturing operations.
The company subsequently announced a major order from NTPC Renewable Energy Limited.
₹558.29 Crore NTPC Order
In July 2026, Insolation Green Energy Private Limited, a wholly owned subsidiary of Insolation Energy, secured a ₹558.29 crore PV-module supply order from NTPC Renewable Energy Limited.
The order relates to a utility-scale solar project in Lalitpur, Uttar Pradesh.
The contract covers supply of M10R N-Type TOPCon Dual-Glass Bifacial Solar PV Modules.
This is strategically relevant because the customer is a major government-linked renewable-energy platform and the order demonstrates INA Solar’s participation in utility-scale projects.
Distribution Network
The company has built a sizeable distribution network.
Management currently reports:
- 40,000+ customers
- 1,000+ channel partners
- Presence in 250+ districts
- 400+ MW of IPP projects
The channel network provides access to the residential, commercial and industrial solar markets in addition to utility-scale projects.
Government & Institutional Opportunities
INA Solar is positioned to benefit from India’s continuing expansion of solar generation.
Relevant demand areas include:
- PM-KUSUM
- Rooftop solar
- Utility-scale solar
- Government renewable-energy projects
- Commercial & industrial solar
- Solar parks
- Renewable-energy developers
The company has specifically highlighted EPC activity under KUSUM A & C, IPPs, solar parks and rooftop projects.
Industry Outlook
India’s solar industry continues to expand as the country adds renewable-generation capacity.
The growth opportunity for domestic manufacturers is supported by:
- Increasing solar installations
- Domestic manufacturing policies
- ALMM requirements
- Import-substitution efforts
- Renewable-energy targets
- Government support for domestic manufacturing
- Rising demand for high-efficiency modules
However, the industry is also highly competitive and capital intensive.
Competitive Landscape
Relevant listed competitors and comparable companies include:
- Waaree Energies
- Premier Energies
- Vikram Solar
- Websol Energy System
- Borosil Renewables
- Insolation Energy
The competitive landscape varies because some companies have greater upstream integration while others focus primarily on module manufacturing.
INA Solar’s strategy is moving toward greater vertical integration through solar cells and aluminium frames.
Competitive Position
1. Rapid Capacity Expansion
The company has increased module capacity from 80 MW in 2017 to 5.5 GW currently.
2. Strong Recent Revenue Growth
Revenue increased from approximately ₹737 crore in FY24 to ₹1,334 crore in FY25 and ₹2,164 crore in FY26.
3. Improving Profitability
FY26 EBITDA increased 76.5%, ahead of revenue growth of 61.0%.
4. Backward Integration
The planned 4.5 GW solar-cell and 18,000 MTA aluminium-frame capacity could increase internal sourcing over time.
5. Customer Diversification
The company operates through:
- Channel partners
- Utility-scale customers
- Government projects
- IPPs
- Residential customers
- Commercial customers
- Industrial customers
Key Growth Drivers
Solar Manufacturing Expansion
The 5.5 GW module capacity provides a significantly larger revenue opportunity than the company’s historical manufacturing base.
Solar Cell Manufacturing
The planned 4.5 GW cell capacity could improve vertical integration and reduce dependence on external cell suppliers.
Aluminium Frame Manufacturing
The planned 18,000 MTA capacity can further integrate a key module component.
Utility-Scale Orders
Large orders such as the ₹558.29 crore NTPC Renewable Energy contract can support capacity utilisation and revenue visibility.
PM-KUSUM
Solar pumps and decentralised solar generation provide additional demand opportunities.
Rooftop Solar
Residential and commercial rooftop installations create a large distributed market.
Key Risks
1. Solar Module Price Competition
Solar manufacturing is highly competitive.
Aggressive pricing by domestic and international manufacturers can compress margins.
2. Technology Risk
Solar technology is evolving quickly.
TOPCon, HJT and future technologies can reduce the economic life of existing manufacturing lines.
The company’s own annual report identifies technological obsolescence as a potential risk.
3. Raw-Material Price Risk
Module economics are affected by prices of:
- Cells
- Wafers
- Silicon
- Glass
- Aluminium
- EVA
- Backsheets
4. Working-Capital Requirements
Rapid revenue growth can require significant working capital.
Solar manufacturers typically need substantial inventory and receivables financing.
5. Capacity-Expansion Risk
The company is simultaneously expanding into solar cells and aluminium frames.
Large capex projects create:
- Execution risk
- Financing requirements
- Commissioning risk
- Capacity-utilisation risk
6. Margin Normalisation
FY25 and FY26 showed very strong EBITDA and PAT growth.
Maintaining the same rate of margin expansion may become increasingly difficult as the company scales.
7. Customer Concentration
Large utility orders can create significant individual-contract exposure.
8. Policy Risk
Changes in:
- ALMM
- Import duties
- Domestic-content requirements
- Solar subsidies
- Government procurement
can affect industry economics.
Share Price
Insolation Energy is now a listed company.
On 18 September 2026, the share closed around ₹92.90, according to Business Standard. Its reported market capitalisation was approximately ₹2,048 crore.
The stock’s 52-week range was approximately ₹81 to ₹219.95.
Because the stock has recently migrated to the Main Board, investors should be cautious when comparing its current valuation with its historical SME-market valuation.
Market Capitalisation
Using approximately 220.39 million shares outstanding and a share price of ₹92.90:
Market Capitalisation ≈ ₹2,047–2,048 crore
This is consistent with the market-capitalisation data reported on September 18, 2026.
Valuation
FY26 P/E
FY26 PAT:
₹200.47 crore
Shares outstanding:
~22.04 crore
Approximate FY26 EPS:
₹9.09
At ₹92.90 per share:
FY26 P/E ≈ 10.2x
This is an approximate calculation using the company’s reported consolidated FY26 PAT and the number of shares listed in March 2026.
Q1 FY27 Annualised EPS
Q1 FY27 EPS:
₹1.73
A simple annualisation gives:
₹1.73 × 4 = ₹6.92
However, this is only a mechanical annualisation and should not be treated as a forecast.
The FY26 EPS of approximately ₹9.09 is currently the more useful historical reference point.
Valuation Framework
For Insolation Energy, the key valuation variables are:
Revenue growth
Module capacity utilisation
EBITDA margin
Solar-cell integration
Working-capital intensity
Capex efficiency
=
Future EPS / FCF
The company is transitioning from a relatively small solar manufacturer into a multi-GW integrated renewable-energy manufacturing platform.
Therefore, investors should focus on whether the company’s return on incremental capital remains attractive as it expands.
Important Financial Metrics
| Metric | FY24 | FY25 | FY26 |
|---|---|---|---|
| Revenue | ₹737 Cr | ₹1,334 Cr | ₹2,164 Cr |
| EBITDA | ~₹84 Cr | ₹170 Cr | ₹305 Cr |
| PAT | ₹55 Cr | ₹126 Cr | ₹200 Cr |
| EPS | ₹2.66 | ₹5.95 | ~₹9.09 |
| Revenue Growth | — | ~81% | ~61% |
| PAT Growth | — | ~128% | ~59% |
FY25 and FY26 figures are based on reported consolidated results.
Q1 FY27 Snapshot
| Metric | Q1 FY27 |
|---|---|
| Revenue | ₹745.40 Cr |
| EBITDA | ₹76.87 Cr |
| PBT | ₹47.50 Cr |
| PAT | ₹38.02 Cr |
| EPS | ₹1.73 |
What Investors Should Monitor
For the next 2–3 years, the most important indicators are:
- Module capacity utilisation
- Solar-cell plant commissioning
- Aluminium-frame plant commissioning
- Order-book growth
- Revenue growth
- EBITDA margin
- Working-capital days
- Inventory levels
- Receivables
- Debt
- Capex
- ROCE
- Cash-flow conversion
- TOPCon technology adoption
- Large utility orders
- PM-KUSUM orders
- Domestic-content policy
- Solar-module ASP trends
Investment Thesis – Business Drivers
The company has moved rapidly from an 80 MW manufacturing operation in 2017 to a reported 5.5 GW module manufacturing platform.
The FY25–FY26 financial performance demonstrates that this expansion has translated into significant revenue and earnings growth.
FY26 revenue exceeded ₹2,100 crore while PAT crossed ₹200 crore.
The company is also moving upstream through planned solar-cell and aluminium-frame manufacturing.
At the same time, the ₹558.29 crore NTPC Renewable Energy order and a previously reported 2.1 GW order book provide evidence of demand visibility.
Key Concerns
The main concern is that rapid growth can create a mismatch between:
Revenue growth
and
cash-flow generation / capital requirements.
The company is expanding manufacturing capacity aggressively, so investors need to monitor whether incremental capacity generates adequate returns.
The second concern is industry cyclicality.
Solar-module manufacturing can experience periods of:
- Oversupply
- Price compression
- Inventory losses
- Margin pressure
- Rapid technology changes
Therefore, FY25–FY26 growth rates should not automatically be extrapolated indefinitely.
Corporate Information
Company: Insolation Energy Limited
Brand: INA Solar
CIN: U31909RJ2015PLC048671
Incorporated: October 15, 2015
Registered Office: Jaipur, Rajasthan
Corporate Office: Fluidcon House, C-02, New Aatish Market Extension, Jaipur, Rajasthan
NSE Symbol: INA
BSE Code: 543620
ISIN: INE0LGX01024
Face Value: ₹1
Status: Listed on NSE & BSE Main Board
The company’s corporate office is in Jaipur and it also maintains a regional office in New Delhi.
Important Links
Official Website:
Insolation Energy / INA Solar
Investor / Annual Reports:
INA Solar – Investor Information
FY2024-25 Annual Report:
Insolation Energy FY25 Annual Report
FY26 Results:
Insolation Energy FY2025-26 Results
Q1 FY27 Results:
Insolation Energy Q1 FY27 Results
NSE/BSE Main Board Migration:
INA Solar Main Board Listing
Conclusion
Insolation Energy has undergone a significant transformation over the last several years.
The company has expanded from an 80 MW solar-module manufacturer in 2017 to a 5.5 GW module-manufacturing platform, while simultaneously building an EPC business and preparing for upstream integration into solar cells and aluminium frames.
Financial growth has been substantial.
Revenue increased from approximately ₹737 crore in FY24 to ₹1,334 crore in FY25 and ₹2,164 crore in FY26, while PAT increased from approximately ₹55 crore to ₹126 crore and then ₹200 crore over the same period.
The company also entered FY27 with strong operating momentum, reporting Q1 revenue of ₹745 crore and PAT of ₹38 crore.
The strategic direction is increasingly toward an integrated solar-manufacturing model:
Solar Cells → Modules → Aluminium Frames → EPC → Solar Projects
The ₹558.29 crore NTPC Renewable Energy order and the reported 2.1 GW order book provide additional demand visibility.
However, the company’s future performance will depend heavily on whether it can maintain healthy margins while scaling capacity. Solar manufacturing is highly competitive, technologically dynamic and exposed to module-price and raw-material cycles.
At approximately ₹92.90 per share on September 18, 2026, the company had a market capitalisation of approximately ₹2,048 crore. Using FY26 PAT of ₹200.47 crore gives an approximate trailing P/E of 10.2x.
The key question for investors is therefore not simply whether solar demand will grow, but whether INA Solar can convert its rapid capacity expansion into sustainable free cash flow and attractive returns on capital.
Disclaimer
This report is prepared for informational and research purposes only and does not constitute investment advice.
Financial information is based primarily on company disclosures, annual reports and publicly available exchange information.
Share prices and market capitalisation are subject to market fluctuations. The price referenced in this report is the reported closing price on September 18, 2026 and should not be treated as a future price target.
Future earnings, margins, capacity utilisation and project execution may differ materially from historical performance.
Investors should independently review the latest financial statements, exchange filings, shareholding pattern, debt, cash flows, related-party transactions, contingent liabilities and regulatory disclosures before making an investment decision.
The author of this report is not a SEBI-registered Research Analyst unless separately stated.
For more such unlisted stocks visit https://unlistedcart.com/unlisted-shares/
