
1. Company Overview
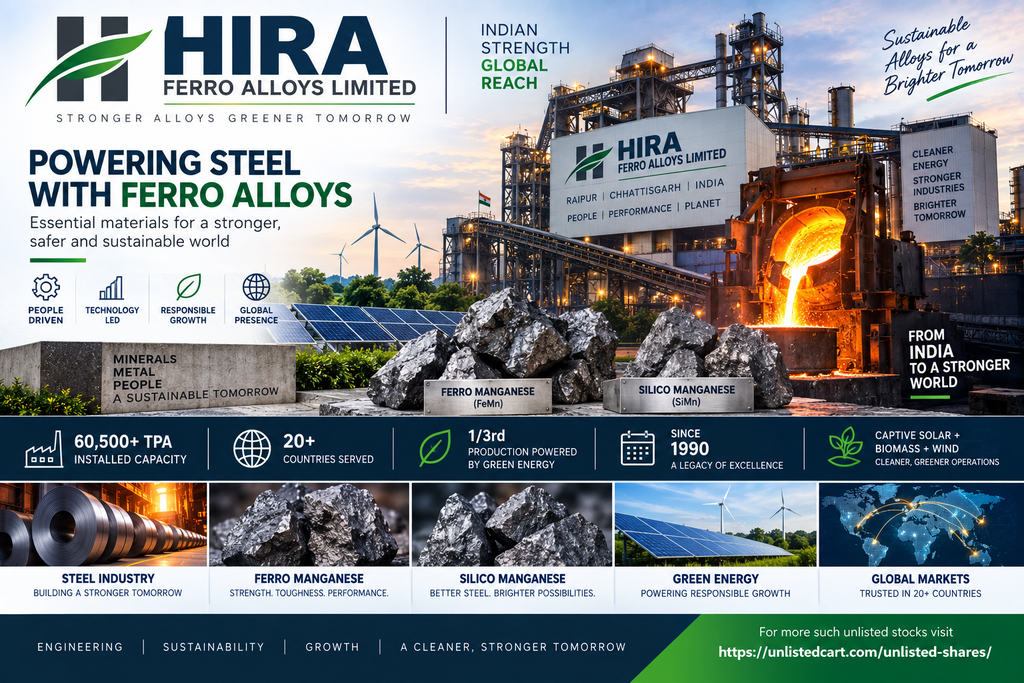
Hira Ferro Alloys Limited (HFAL) is a Raipur, Chhattisgarh-based manufacturer of manganese-based ferro alloys, primarily used in steel manufacturing. The company was established in 1990 and is part of the broader Hira Group. It has developed an integrated model combining ferro-alloy manufacturing with captive and renewable power generation. (hiraferroalloys.com)
Official Website – Hira Ferro Alloys
The company describes itself as a producer and exporter of green/low-carbon ferro alloys and currently serves customers in 20+ countries. (hiraferroalloys.com)
2. What Does Hira Ferro Alloys Manufacture?
HFAL primarily manufactures manganese-based ferro alloys, which are important inputs in steelmaking.
Major Products
- High Carbon Ferro Manganese 70–75%
- High Carbon Ferro Manganese 65–70%
- High Carbon Silico Manganese 65%
- High Carbon Silico Manganese 60%
These alloys are used to improve properties such as strength, toughness, hardness and wear resistance in steel. (hiraferroalloys.com)
The company also has exposure to power generation and related industrial products.
3. Manufacturing Capacity
Hira Ferro Alloys has an installed ferro-alloy production capacity of approximately 60,500 tonnes per annum, according to its official website. (hiraferroalloys.com)
Its operations are based in the Urla Industrial Complex, Raipur, Chhattisgarh, providing proximity to raw-material sources and the Indian steel industry. (hiraferroalloys.com)
Power Infrastructure
One of HFAL’s important differentiators is its captive/renewable power infrastructure.
The company reports:
| Power Source | Capacity |
|---|---|
| Solar | 55 MW* |
| Thermal | 20 MW |
| Biomass | 8.5 MW |
| Wind | 1.5 MW |
*The company has stated that its solar project was commissioned at 52 MWp initially, with efforts to install the balance capacity. (hiraferroalloys.com)
This integrated power model is relevant because electricity is a major cost component in ferro-alloy manufacturing.
4. Green Ferro Alloys
HFAL has positioned itself around low-carbon ferro-alloy production.
The company states that approximately one-third of its ferro-alloy production is powered by green-energy sources, using solar, wind and biomass. (hiraferroalloys.com)
It also highlights:
- Zero liquid discharge initiatives
- Waste recycling
- Renewable energy integration
- Lower-carbon manufacturing
- Energy-efficiency initiatives
The company states that its processes help achieve approximately 30% lower carbon emissions compared with traditional manufacturing and around 25% reduction in energy consumption. These are company-stated figures and should be viewed in that context. (hiraferroalloys.com)
5. Financial Performance
FY26 vs FY25
| Particulars | FY25 | FY26 | Change |
|---|---|---|---|
| Revenue from Operations | ₹596.26 Cr | ₹540.28 Cr | -9.4% |
| Total Revenue | ₹604.28 Cr | ₹549.68 Cr | -9.0% |
| PBT | ₹42.13 Cr | ₹42.53 Cr | +1.0% |
| PAT | ₹30.76 Cr | ₹25.26 Cr | -17.9% |
| EPS | ₹13.27 | ₹10.90 | -17.9% |
| Finance Cost | ₹18.30 Cr | ₹17.60 Cr | Lower |
FY26 revenue declined, but profit before tax remained broadly stable. PAT declined because of a higher tax provision, according to the FY26 financial data. (Wealth Wisdom)
The company’s FY25 performance had been considerably stronger than FY24: revenue from operations rose to about ₹596 crore from ₹346 crore, while PAT increased to approximately ₹30.8 crore from ₹8.2 crore. (hiraferroalloys.com)
6. Production Performance
FY25 saw a significant increase in ferro-alloy production.
| Particulars | FY24 | FY25 |
|---|---|---|
| Ferro Alloy Production | 41,637 MT | 69,667 MT |
| Ferro Alloy Sales | 41,620 MT | 71,640 MT |
The annual report attributed the improvement primarily to stronger steel-sector demand and better price realisation. (hiraferroalloys.com)
This also highlights the cyclical nature of HFAL’s earnings: ferro-alloy prices and volumes can change materially with the steel cycle.
7. Shareholding Pattern
HFAL has historically had a highly concentrated ownership structure.
Current unlisted-market data identifies Godawari Power & Ispat Limited (GPIL) as the largest shareholder with approximately 75.67%, while Dinesh Agrawal is reported with approximately 4.65%. (sbnri.com)
| Shareholder | Approx. Holding |
|---|---|
| Godawari Power & Ispat Ltd. | 75.67% |
| Dinesh Agrawal | 4.65% |
| Other shareholders | Balance |
The historical promoter shareholding was around 95.30%, before subsequent ownership changes. (hiraferroalloys.com)
The acquisition by GPIL is particularly relevant: UnlistedZone reports that GPIL agreed in 2022 to acquire 44.55 lakh HFAL shares from Hira InfraTek, increasing its holding from 56.45% to approximately 75.66%. (UnlistedZone)
8. Parent Group & Strategic Integration
HFAL is a subsidiary of Godawari Power & Ispat Limited (GPIL), part of the larger Hira Group ecosystem.
This creates potential operational synergies because GPIL itself has an integrated steel operation including iron ore, pellets, sponge iron, billets and steel products. CRISIL specifically notes the benefits of HFAL’s integration with the group, including power security and supply-chain synergies. (CRISIL)
9. Current Unlisted Share Price
As of 17 September 2026, SBNRI reports an average unlisted-market price of approximately ₹170 per share. It reports:
- Face Value: ₹10
- Shares Outstanding: 2.31885 crore
- Indicative Market Cap: ~₹447.5 crore
- EPS: ₹10.90
- P/E: ~17.7x
- P/B: ~0.6x
- Book Value: ~₹320/share
- Minimum lot shown by SBNRI: 60 shares
Other unlisted-market platforms show prices around ₹168, demonstrating that private-market quotes can vary by platform, transaction size and liquidity. (BuyUnlistedShares)
Important: These are indicative OTC/unlisted-market reference prices and not NSE/BSE exchange prices.
10. ISIN & Corporate Details
| Particular | Details |
|---|---|
| Company | Hira Ferro Alloys Limited |
| ISIN | INE573I01011 |
| CIN | U27101CT1984PLC005837 |
| Face Value | ₹10 |
| Equity Shares | 2,31,88,500 |
| Registered/Operating Location | Raipur, Chhattisgarh |
| Industry | Ferro Alloys / Metals |
| Status | Unlisted / Delisted |
The company was delisted from the Bombay Stock Exchange in July 2014, according to CRISIL. (CRISIL)
There are some third-party databases that still display old BSE/NSE listing information, so investors should not rely on those legacy records to conclude that HFAL is currently exchange-traded. Current unlisted-market sources and CRISIL identify it as an unlisted/delisted company. (CRISIL)
11. Credit Profile
CRISIL reaffirmed HFAL’s ratings in May 2026:
- Long-term: CRISIL A+/Stable
- Short-term: CRISIL A1
- Rated bank facilities: approximately ₹147 crore
CRISIL’s FY25 data showed revenue of ₹596 crore, PAT of ₹30.76 crore and adjusted debt/net worth of 0.19x. (CRISIL)
This indicates a relatively moderate debt position compared with the company’s asset base, although commodity-cycle earnings remain an important consideration.
12. Key Growth Drivers
1. Steel Industry Growth
Ferro alloys are essential inputs in steel production. Growth in Indian steel capacity and infrastructure spending can support long-term demand.
2. Captive Power
Ferro-alloy production is electricity intensive. Captive and renewable power generation can provide cost and supply advantages.
3. Green Steel Ecosystem
As global steel producers face increasing pressure to reduce carbon emissions, demand for lower-carbon inputs could create opportunities for HFAL’s green-ferro-alloy positioning.
4. Export Opportunity
The company currently serves customers in 20+ countries, giving it access to international steel markets. (hiraferroalloys.com)
5. GPIL Integration
Being part of an integrated steel group provides potential raw-material, power and customer synergies. (CRISIL)
13. Key Risks
Commodity Price Risk
Ferro-alloy prices can fluctuate significantly depending on steel demand, manganese ore prices and global supply.
Steel-Cycle Dependence
A slowdown in steel production can directly affect ferro-alloy demand.
Power Costs
Although HFAL has captive power, electricity remains a critical factor in ferro-alloy economics.
Raw Material Availability
Manganese ore and other raw materials are important cost components. Changes in availability and prices can affect margins.
Export/Global Market Risk
The company serves international customers, exposing it to global steel cycles, currency movements and international trade conditions.
Earnings Volatility
FY25 was a strong improvement year, but FY26 revenue and PAT declined. Investors should therefore evaluate earnings across a full commodity cycle rather than relying on a single year’s profitability. (Wealth Wisdom)
Unlisted Liquidity
There is no continuous NSE/BSE trading market for the shares. Exiting an unlisted investment can take time and may require accepting a price different from the latest indicative quote.
14. IPO / Listing Status
HFAL is currently an unlisted/delisted company. CRISIL states that the company was delisted from BSE in July 2014. (CRISIL)
Investors should therefore not assume that an IPO or relisting is imminent merely because the shares are available in the unlisted market.
The company’s official investor section currently provides its FY2025-26 annual report and other statutory documents, which are useful for monitoring any future corporate developments. (hiraferroalloys.com)
Hira Ferro Alloys – Investor Corner & Annual Reports
15. Investment Snapshot
| Parameter | Observation |
|---|---|
| Business | Manganese-based Ferro Alloys |
| Established | 1990 |
| Capacity | ~60,500 TPA |
| Location | Raipur, Chhattisgarh |
| FY26 Revenue | ~₹540 Cr |
| FY26 PAT | ~₹25.3 Cr |
| FY26 EPS | ₹10.90 |
| Indicative Unlisted Price | ~₹168–170 |
| Indicative Market Cap | ~₹390–448 Cr |
| Largest Shareholder | GPIL ~75.67% |
| Renewable Power | Solar + Wind + Biomass |
| Customers | 20+ countries |
| Status | Unlisted / Delisted |
| ISIN | INE573I01011 |
16. UnlistedCart Takeaway
Hira Ferro Alloys offers exposure to the ferro-alloy segment with an integrated power model and strong linkage to the steel industry.
The key areas to monitor are:
Ferro-alloy prices + steel demand + production volumes + captive/renewable power + GPIL integration + export demand
against
commodity-cycle volatility + raw-material costs + earnings fluctuations + limited liquidity of unlisted shares.
One particularly important point is the difference between FY25 and FY26: FY25 benefited from stronger ferro-alloy prices and steel demand, while FY26 revenue declined and PAT fell despite relatively stable PBT. This makes cycle-adjusted earnings analysis important when evaluating the company. (hiraferroalloys.com)
Official Hira Ferro Alloys Website
Official Annual Reports & Investor Information
Disclaimer: This report is for informational and educational purposes only and should not be considered investment advice or a recommendation to buy or sell securities. Unlisted shares involve liquidity, valuation, business, commodity-cycle and exit risks. Indicative OTC prices may vary between transactions and platforms. Investors should independently verify financial statements, shareholding, transaction prices and applicable regulatory/tax requirements before investing.
For more such unlisted stocks visit https://unlistedcart.com/unlisted-shares/
