
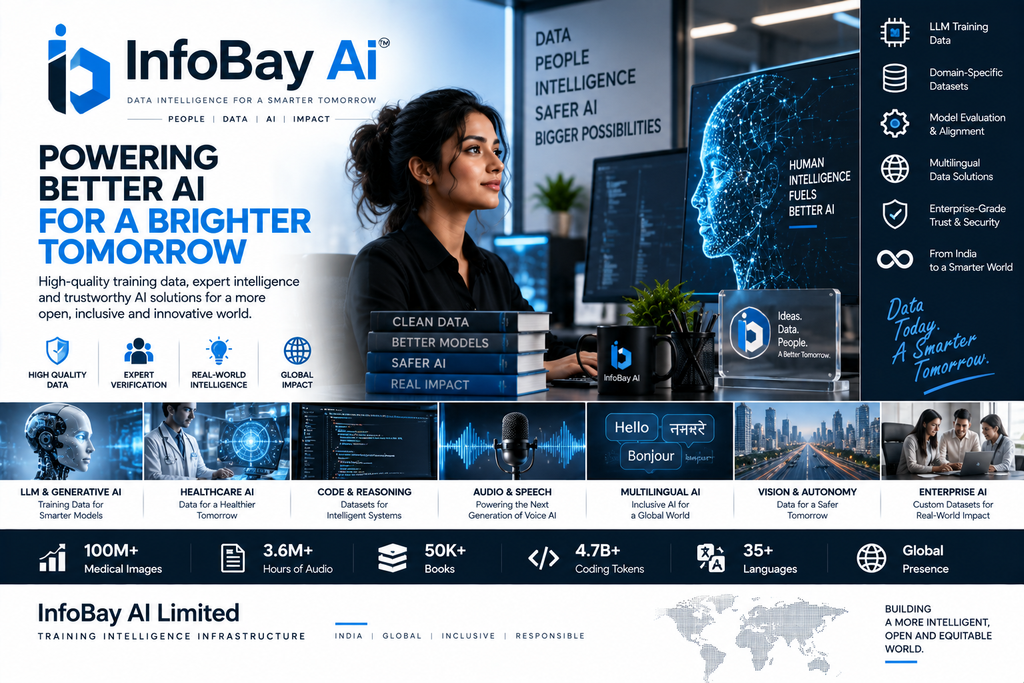
From EduTech to AI Training Intelligence Infrastructure | High-Growth Unlisted AI Opportunity
Company: InfoBay AI Limited
Formerly: EduGorilla Community Private Limited
CIN: U74999UP2016PLC088614
ISIN: INE0SE901014
Incorporated: 23 December 2016
Registered Office: Uttar Pradesh, India
Headquarters / Operations: Lucknow, Uttar Pradesh
Founder & CEO: Rohit Manglik
Co-Founder & CTO: Shashwat Vikram
Status: Active & Unlisted
Sector: Artificial Intelligence / Data Infrastructure / AI Training Data
FY26 Revenue: ~₹107.78 Cr
FY26 EBITDA: ~₹63.39 Cr
FY26 PAT: ~₹48.62 Cr
Indicative Unlisted Price: ~₹3.25–₹3.60 lakh/share
Indicative Market Capitalisation: ~₹750–₹760 Cr
IPO Status: No confirmed DRHP / IPO timeline
1. Executive Summary
InfoBay AI Limited is an Indian AI-data infrastructure company that has undergone a significant transformation from its earlier EduGorilla education/test-preparation business.
The company now positions itself as a training intelligence infrastructure provider for AI models, focusing on expert-verified datasets, data curation, annotation, evaluation, RLHF/SFT workflows and post-training optimisation.
Its services are designed for AI companies developing:
- Large Language Models
- Enterprise AI
- Voice AI
- Medical AI
- Coding models
- Reasoning models
- AI safety and alignment systems
The transformation is visible in the financial numbers.
FY25 revenue was approximately ₹48.41 Cr, which increased to approximately ₹107.78 Cr in FY26, representing growth of around 123%.
More importantly, PAT increased from approximately ₹16.27 Cr to ₹48.62 Cr, representing nearly 199% growth. EBITDA increased from approximately ₹25.18 Cr to ₹63.39 Cr.
This makes InfoBay one of the more interesting high-growth AI-focused unlisted companies, although its valuation and the sustainability of the exceptional FY26 growth rate require careful examination.
2. Company Overview
InfoBay was incorporated in December 2016 under the name EduGorilla Community Private Limited.
The company originally focused on:
- Competitive-examination preparation
- Test series
- Educational content
- Online learning
- Creator/course platforms
- Assessment and evaluation
It subsequently evolved into InfoBay AI, with its current business centred around AI data and model-training infrastructure.
The company’s current positioning is substantially different from its historical EdTech identity.
Its own website describes InfoBay as a “Training Intelligence Infrastructure” company focused on making AI systems more accurate, factual and production-ready.
3. Business Model
InfoBay’s business can broadly be divided into several AI-data services.
A. Pre-Training Data Curation
The company develops and curates structured datasets that can be used during model pre-training.
Its datasets cover areas including:
- Text
- Books
- Audio
- Images
- Technical content
- Multilingual datasets
B. SFT Dataset Design
Supervised Fine-Tuning (SFT) datasets help AI models learn how to respond to specific instructions and tasks.
InfoBay focuses on expert-created and structured datasets rather than generic crowd-sourced labelling.
C. RLHF & Reward Modelling
The company provides human-verified data used in:
Reinforcement Learning from Human Feedback (RLHF)
and related model-alignment workflows.
D. AI Evaluation
InfoBay evaluates AI systems for:
- Factuality
- Reasoning
- Hallucinations
- Safety
- Bias
- Model performance
E. Medical AI Data
The company claims substantial healthcare datasets involving medical images and patient records for AI training and radiology/clinical applications.
F. Coding & Reasoning Data
InfoBay also develops coding datasets for AI systems designed for:
- Code generation
- Algorithmic reasoning
- Programming assistants
- Developer copilots
4. Why AI Training Data Is Becoming Valuable
Large AI models require enormous quantities of high-quality data.
However, the industry is gradually moving away from simply acquiring more data toward obtaining:
Better, cleaner, more specialised and more accurately labelled data.
This creates a potential opportunity for companies like InfoBay.
For advanced AI models, data quality can influence:
- Accuracy
- Reasoning
- Factuality
- Multilingual capability
- Safety
- Domain expertise
- Hallucination rates
InfoBay therefore attempts to operate higher up the AI-data value chain rather than competing purely as a commodity data-labeling company. Its website explicitly describes the company as an AI training-intelligence infrastructure provider rather than a conventional labeling shop.
5. Data Assets
InfoBay’s current website highlights a substantial proprietary/curated data infrastructure.
| Data Category | Company-Reported Scale |
|---|---|
| Audio | 3.6M+ hours |
| Books | 50,000+ |
| Q&A | 9.2M+ |
| Digital artifacts | 4.4M+ |
| Coding tokens | 4.7B+ |
| Languages | 35+ |
| Medical images | 100M+ claimed |
| Patient records | 2.5M+ claimed |
These figures are company-reported operating metrics, rather than independently audited financial metrics, and should therefore be interpreted accordingly.
6. Global Expansion
InfoBay has expanded its operating footprint beyond India.
The company currently highlights operations/capability centres across:
- India
- Indonesia
- Kenya
- Philippines
- Uganda
- UAE
- Nepal
- Other international markets
A July 2026 company announcement stated that InfoBay had expanded into five countries and planned to reach 14 countries by 2027.
This internationalisation could become important because the demand for multilingual AI data is global rather than India-specific.
7. Financial Performance
FY25 vs FY26
| ₹ Cr | FY25 | FY26 | Growth |
|---|---|---|---|
| Net Revenue | 48.41 | 107.78 | +122.6% |
| EBITDA | 25.18 | 63.39 | +151.8% |
| PBT | 22.77 | 65.17 | +186.2% |
| PAT | 16.27 | 48.62 | +198.8% |
| EBITDA Margin | 52.0% | 58.8% | Improved |
| PAT Margin | 33.6% | 45.1% | Improved |
The FY26 financial numbers indicate not merely revenue growth but strong operating leverage.
Revenue more than doubled, while EBITDA grew even faster and PAT nearly tripled.
8. FY26 — What Stands Out
The most impressive part of the FY26 results is the margin profile.
Revenue
₹107.78 Cr
EBITDA
₹63.39 Cr
EBITDA Margin
~58.8%
PAT
₹48.62 Cr
PAT Margin
~45.1%
For an AI-data business, these margins are potentially attractive if they prove sustainable.
However, investors should avoid extrapolating FY26’s 123% revenue growth indefinitely.
The key question is:
Can InfoBay maintain high growth while preserving its unusually strong margins as the business scales?
9. Revenue Transformation
One of the most significant changes in InfoBay is the source of revenue.
According to available company/industry analysis, approximately 98% of FY26 revenue came from AI-focused data activities, while the legacy education/test-preparation business contributed less than 2%.
This represents a dramatic strategic transformation.
Earlier Model
EduGorilla → Test Preparation → EdTech
Current Model
InfoBay AI → Data → AI Training → Model Evaluation → Enterprise AI Infrastructure
The second business has a much larger global addressable market.
10. Founder & Management
Rohit Manglik
Founder & CEO
Rohit Manglik has been associated with the company since its incorporation and remains its key promoter/management figure.
Shashwat Vikram
Co-Founder & CTO
Shashwat Vikram joined the board in 2022 and is identified as the company’s technology leadership figure.
Pushpa Manglik
Director / Promoter
Pushpa Manglik is also associated with the promoter group.
The combination of founder leadership and technical management is particularly important for a technology-intensive business.
11. Funding History
InfoBay’s earlier development was supported by venture investors and angel investors during its EduGorilla phase.
Reported investors have included:
- Auxano Capital
- SucSEED Indovation Fund
- Mumbai Angels
- Lead Angels
- TiE India
- Other angel and venture investors
However, publicly reported historical funding figures vary significantly between databases.
One source estimates total funding at approximately $6.34 million, while other datasets show materially different totals.
Therefore, the exact cumulative funding figure should not be treated as definitive without reconciliation against company filings.
12. Shareholding & Capital Structure
The capital structure is more complex than a conventional founder-owned private company.
FY25 filings analysed by independent researchers showed:
| Category | Approx. FY25 Position |
|---|---|
| Promoter Equity | ~68.46% |
| Non-Promoter Individuals | ~30.81% |
| Corporate Equity | ~0.73% |
| Preference Shares | Significant non-promoter ownership |
The company has also had preference/convertible securities and venture-capital participation.
This is important because the headline share price cannot be used alone to calculate valuation unless the fully diluted capital structure is understood.
13. Current Unlisted Share Price
Recent private-market references are unusually high on a per-share basis.
Recent quotes include approximately:
₹3.25 lakh – ₹3.60 lakh per share
with one recent marketplace reference showing ₹3.60 lakh and another recent research publication showing ₹3.25 lakh.
Another intermediary recently quoted approximately ₹2.55 lakh.
This wide variation highlights an important characteristic of unlisted shares:
The quoted price is an indicative OTC price, not an exchange-discovered market price.
Prices can change significantly depending on availability, lot size, demand and transaction counterparties.
14. Indicative Valuation
A recent private-market reference places InfoBay’s market capitalisation around:
₹750–₹760 Cr
At approximately ₹3.25 lakh/share, the valuation is roughly:
₹750+ Cr
Against FY26 PAT of approximately ₹48.62 Cr, this implies a broad earnings multiple in the mid-teens.
One recent market reference indicates a P/E of approximately 15.6x at a ₹3.25 lakh price.
Another intermediary’s valuation framework is substantially more expensive, illustrating the sensitivity to transaction price and capital-structure assumptions.
Valuation Snapshot
| Metric | Approx. |
|---|---|
| Indicative Price | ₹3.25–₹3.60 lakh |
| Market Cap | ~₹750–₹760 Cr |
| FY26 Revenue | ₹107.78 Cr |
| FY26 EBITDA | ₹63.39 Cr |
| FY26 PAT | ₹48.62 Cr |
| Indicative P/E | ~15–16x at ₹3.25 lakh |
| P/B | Data varies by capital structure |
| Listing | Unlisted |
15. Is the Valuation Attractive?
On FY26 earnings alone, the valuation appears much more reasonable than the headline share price suggests.
This is because the company has:
- ~₹108 Cr revenue
- ~₹63 Cr EBITDA
- ~₹49 Cr PAT
- ~45% PAT margin
- ~59% EBITDA margin
At a ~₹750 Cr equity value, the company trades at approximately 15–16x FY26 PAT.
For a rapidly growing AI-data company, that is not automatically expensive.
However, there are three major caveats:
1. FY26 Growth May Not Repeat
A 123% revenue increase is difficult to sustain.
2. Customer Concentration
AI-data businesses can become dependent on a relatively small number of large clients.
3. Business Transition Is Recent
The transformation from EduGorilla to InfoBay AI is relatively recent, meaning the current business model does not yet have a long operating history.
16. Competitive Advantages
Expert-Verified Data
High-quality expert data can be more valuable than commodity annotation.
Multilingual Capability
India and emerging markets provide access to languages that are relatively underrepresented in AI training datasets.
Domain Expertise
Healthcare, legal, finance, coding and other specialist domains require higher-quality human verification.
Proprietary Data Infrastructure
InfoBay says it has developed proprietary annotation and evaluation infrastructure rather than operating solely as a manpower-based data-labeling business.
High Margins
FY26 EBITDA margin of approximately 59% is a major positive if sustainable.
Global Opportunity
The market for AI training data is global and expanding alongside LLM development.
17. Investment Positives vs Concerns
| Investment Positives | Key Concerns |
|---|---|
| AI-focused business | Very recent business transformation |
| FY26 revenue +123% | Growth sustainability |
| FY26 PAT +199% | Customer concentration |
| EBITDA margin ~59% | Data-security/privacy risks |
| PAT margin ~45% | AI industry competition |
| Global expansion | Dependence on AI spending |
| Expert-verified datasets | Unlisted liquidity |
| Proprietary data infrastructure | High per-share price |
| Founder-led management | Complex capital structure |
| Large AI market opportunity | No confirmed IPO |
18. Key Growth Drivers
1. Explosion in AI Model Development
More AI models mean more demand for training and evaluation data.
2. Shift Toward High-Quality Data
As models become more capable, low-quality generic data becomes less useful.
3. Multilingual AI
Demand for regional-language AI could create significant opportunities for InfoBay.
4. Healthcare AI
Healthcare requires specialist, structured and carefully validated datasets.
5. AI Coding
Coding models need large volumes of high-quality programming examples and reasoning data.
6. Model Evaluation
As AI becomes regulated and deployed in high-stakes environments, factuality and evaluation could become increasingly important.
19. Key Risks
AI Market Risk
The company is heavily exposed to the AI ecosystem.
A slowdown in AI spending or model-development budgets could affect growth.
Customer Concentration
Large AI clients can represent substantial revenue.
Losing one major contract could have a material impact.
Data Privacy
Healthcare and other sensitive datasets require strong compliance, security and governance.
Competition
The company competes indirectly with global data providers, AI-data platforms, specialised annotation firms and internal data teams of large AI companies.
Rapid Technology Change
AI infrastructure changes quickly.
A service that is valuable today may become commoditised tomorrow.
Unlisted Liquidity
There is no NSE/BSE market.
Selling may require finding a private buyer.
Valuation Risk
Even after strong FY26 growth, future valuation depends on the sustainability of growth and margins.
Capital Structure Complexity
Preference shares and other securities mean investors should evaluate the fully diluted capital structure before calculating ownership and valuation.
20. IPO / Listing Status
Currently Unlisted
InfoBay AI Limited remains unlisted on NSE/BSE.
There is currently no verified DRHP or confirmed IPO date identified.
Its conversion into a public limited company in 2026 could be viewed as a corporate-development step, but it should not be interpreted as confirmation of an IPO.
Therefore:
InfoBay AI should currently be treated as an unlisted AI-growth company, not a confirmed pre-IPO company.
21. What Could Trigger Re-Rating?
IPO Filing
A formal DRHP would significantly improve liquidity visibility and potentially increase institutional interest.
Sustained 50%+ Growth
If InfoBay can maintain high growth for several years, current valuation could become more attractive.
Enterprise Client Expansion
Adding large global AI clients could strengthen revenue visibility.
Higher Recurring Revenue
Long-term data contracts and recurring enterprise engagements would improve predictability.
International Expansion
Expansion into additional AI markets could increase the addressable customer base.
AI Data Moat
If proprietary datasets and expert networks become difficult for competitors to replicate, margins could remain attractive.
22. Key KPIs to Monitor
For InfoBay, investors should monitor:
1. Revenue Growth
Can the company sustain 40–50%+ growth?
2. EBITDA Margin
Can the ~59% FY26 margin remain above 40–50%?
3. PAT Margin
FY26 PAT margin of ~45% is unusually high and should be monitored carefully.
4. Client Concentration
What percentage of revenue comes from the top five clients?
5. Recurring Revenue
How much revenue is contractual/repeat versus project-based?
6. Data Asset Growth
Growth in proprietary datasets and expert networks.
7. International Revenue
Percentage of revenue generated outside India.
8. Cash Flow
High accounting profit should ultimately translate into strong operating cash flow.
23. Investment View
InfoBay AI — One of the More Interesting AI-Focused Unlisted Stories
InfoBay AI is an unusual unlisted-company opportunity because its current business is moving beyond conventional EdTech.
The transformation from EduGorilla → InfoBay AI places the company in one of the fastest-growing technology segments globally:
AI training data + model evaluation + post-training intelligence
FY26 numbers are particularly impressive:
Revenue: ₹107.78 Cr
EBITDA: ₹63.39 Cr
PAT: ₹48.62 Cr
And the company achieved these numbers with exceptionally high margins.
At an indicative valuation around ₹750–760 Cr, the company is not obviously expensive relative to FY26 earnings.
However, the market is likely to value InfoBay based on future growth, not simply FY26 earnings.
The key question is therefore:
Can InfoBay convert the current AI-data growth into a scalable, recurring global AI-infrastructure business?
If the answer is yes, the company could have substantial long-term potential.
If FY26 growth proves temporary or margins normalise sharply, the current valuation could become much less attractive.
24. Overall Assessment
| Factor | Assessment |
|---|---|
| AI Industry Opportunity | ⭐⭐⭐⭐⭐ |
| Revenue Growth | ⭐⭐⭐⭐⭐ |
| FY26 Profitability | ⭐⭐⭐⭐⭐ |
| EBITDA Margin | ⭐⭐⭐⭐⭐ |
| Business Scalability | ⭐⭐⭐⭐ |
| Global Opportunity | ⭐⭐⭐⭐ |
| Competitive Moat | ⭐⭐⭐⭐ |
| Financial Visibility | ⭐⭐⭐ |
| Management | ⭐⭐⭐⭐ |
| Valuation | ⭐⭐⭐⭐ |
| Liquidity | ⭐⭐ |
| IPO Visibility | ⭐⭐ |
| Overall Risk | HIGH |
25. Conclusion
InfoBay AI represents a fascinating transformation story.
The company began as EduGorilla, an EdTech/test-preparation business, but has increasingly repositioned itself around AI training data, expert verification, model evaluation and post-training infrastructure.
The transformation appears to be reflected in its financial performance.
FY26 revenue more than doubled to approximately ₹107.8 Cr, while PAT increased nearly threefold to ₹48.6 Cr.
The company’s reported margins are also exceptionally strong.
However, investors should remain disciplined.
The current AI-data business has a relatively short demonstrated history, and the industry is evolving rapidly. Customer concentration, data privacy, technological disruption and the ability to maintain current margins are key risks.
Investment Positioning
InfoBay AI — High-Growth AI Data Infrastructure Company | Strong FY26 Financial Momentum | High-Risk Unlisted Growth Opportunity
Investment Thesis
Positive:
AI demand + expert-verified data + strong growth + high margins + global opportunity.
Negative:
Young business model + customer concentration + rapid AI disruption + unlisted liquidity + no confirmed IPO.
Bottom Line
InfoBay AI is potentially one of the more interesting AI-focused companies in India’s unlisted market, but investors should underwrite the sustainability of its FY26 growth and margins rather than simply extrapolate them forward.
Disclaimer
This report is prepared for informational and research purposes only and does not constitute investment advice, a recommendation, solicitation or an offer to buy or sell securities.
InfoBay AI Limited is an unlisted company. Unlisted-share prices are indicative OTC/private-market references and may vary significantly depending on availability, transaction size, liquidity and counterparty.
Certain operational metrics relating to datasets, clients, geographic expansion and business capabilities are based on company disclosures and should not be interpreted as independently audited operating statistics.
Financial figures should be independently verified against the latest audited financial statements and statutory filings before making an investment decision.
Investors should also evaluate the fully diluted capital structure, including equity, preference shares, ESOPs and other securities, before assessing the company’s effective valuation and ownership.
For more such unlisted stocks visit https://unlistedcart.com/unlisted-shares/
