
Sector: Telecom Infrastructure / EPC / Renewable Energy / Smart Infrastructure
Status: Unlisted Public Company / Pre-IPO
CIN: U72900TN2013PLC091205
ISIN: INE1K1L01010
Incorporated: 17 May 2013
Registered Office: Chennai, Tamil Nadu
Face Value: ₹10 per share
Indicative Unlisted Price: ~₹360–₹375/share
Indicative Market Capitalisation: ~₹800–₹830 Cr
IPO Status: IPO process announced by the company; no exchange listing yet
Current unlisted-market sources indicate approximately ₹360–₹375 per share, with lot sizes varying by intermediary. Prices in the unlisted market are indicative and may differ significantly depending on quantity and transaction terms.
About the Company
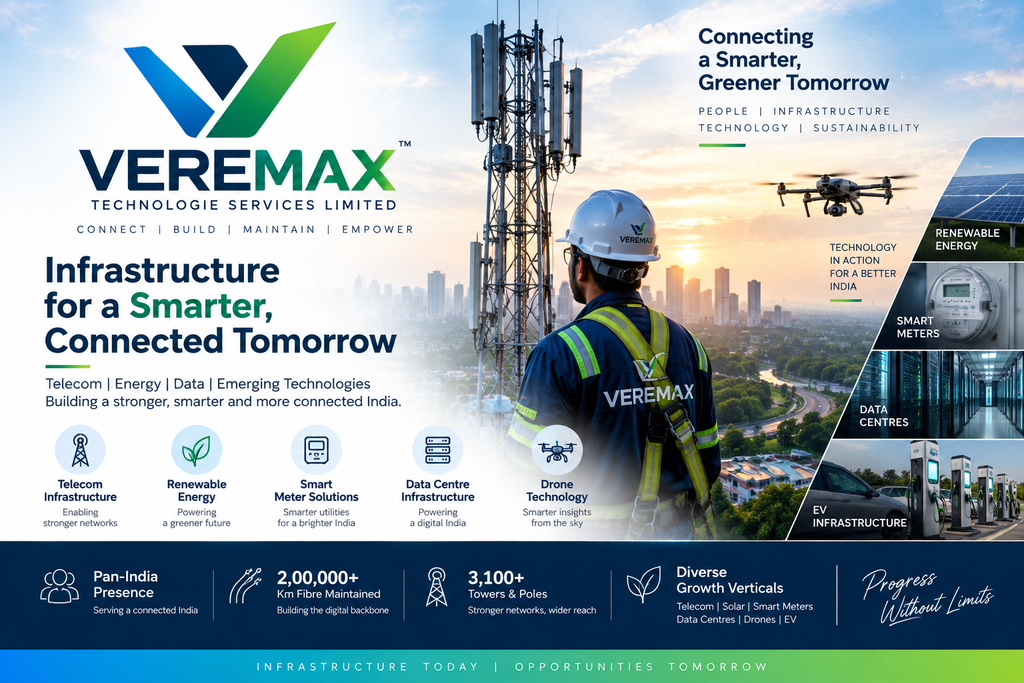
Veremax Technologie Services Limited is a Chennai-based telecom infrastructure company providing end-to-end telecom service integration, project implementation and operations & maintenance services.
Its core activities include fibre infrastructure, tower maintenance, network deployment, telecom O&M and infrastructure leasing. The company has subsequently diversified into renewable energy, smart meters, data centres, drones and EV charging infrastructure.
The company says it operates across multiple Indian states and has developed significant telecom infrastructure capabilities, including fibre networks, tower installation and maintenance.
Important: Veremax is better classified as an infrastructure/EPC and telecom-services company rather than a pure technology or software company.
Key Highlights
| Particular | Details |
|---|---|
| Core Business | Telecom Infrastructure & O&M |
| Other Verticals | Solar, Smart Meter, Data Centre, Drone, EV Charging |
| Geographic Presence | Pan-India |
| Telecom Focus | 4G/5G, fibre, towers & network infrastructure |
| Infrastructure | 6,130 km owned fibre claimed |
| Tower Infrastructure | 3,100 poles/towers claimed |
| Fibre Maintenance | 2,07,966 km claimed |
| Certifications | ISO 9001, ISO 27001, ISO/IEC 20000-1 |
| IP-1 Licence | Yes |
| Listing | Unlisted |
| IPO | Process announced by company |
Company materials state that it has maintained more than 2 lakh km of fibre, around 66,410 towers, and owns approximately 6,130 km of fibre network. These are company-reported operational metrics.
Business Model
1. Telecom Infrastructure
This remains the company’s core business.
Veremax provides:
- Fibre optic network deployment
- Underground and overhead fibre laying
- Copper-to-fibre migration
- Tower erection
- Tower strengthening
- Cell-site O&M
- Active/passive infrastructure services
- RF & EMF surveys
- In-building solutions
- Tower dismantling and relocation
Acuité describes Veremax as providing end-to-end telecom service integration, project implementation and maintenance of active equipment for telecom operators.
2. Renewable Energy
The company is expanding into solar EPC and O&M.
Activities include:
- Solar project installation
- Civil and electrical works
- Transformer erection
- Power evacuation
- Solar O&M
- Renewable-energy infrastructure
3. Smart Meter / AMI
Veremax is targeting the Advanced Metering Infrastructure market.
Its proposed capabilities include:
- Smart-meter supply
- Installation
- Communication infrastructure
- Head-End Systems
- Meter Data Management Systems
The company has stated an ambition around a large smart-meter execution pipeline.
4. Data Centres
The company plans to develop scalable data-centre infrastructure and related services as a new growth vertical.
5. Drone Technology
Veremax plans to use drones for:
- Tower inspection
- Antenna inspection
- Fibre-route inspection
- Real-time visual monitoring
This is intended to improve infrastructure maintenance efficiency.
6. EV Charging
The company is also developing EV charging infrastructure as part of its broader smart-infrastructure strategy.
FY25 Financial Snapshot
The company’s investor presentation reports the following FY25 numbers, which are specifically identified as unaudited:
| ₹ Crore | FY22 | FY23 | FY24 | FY25 |
|---|---|---|---|---|
| Revenue | 325.49 | 435.39 | 523.05 | 620.01 |
| EBITDA | 9.40 | 26.76 | 41.96 | 105.65 |
| EBITDA Margin | 2.89% | 6.14% | 8.02% | 17.04% |
| PAT | 4.78 | 10.40 | 32.19 | 61.68 |
| PAT Margin | 1.47% | 2.39% | 6.15% | 9.96% |
FY25 revenue increased approximately 18.5% YoY, while EBITDA increased substantially from ₹41.96 Cr to ₹105.65 Cr. The company presentation reports FY25 PAT of ₹61.68 Cr.
Balance Sheet
| ₹ Crore | FY24 | FY25 |
|---|---|---|
| Net Worth | 77.02 | 161.16 |
| Total Assets | 321.41 | 331.60 |
| Current Assets | 240.03 | 255.83 |
| Current Liabilities | 214.89 | 85.07 |
| Non-current Liabilities | 29.50 | 85.37 |
The company presentation indicates a substantial increase in reported net worth during FY25.
Growth Strategy
Veremax is attempting to move beyond traditional telecom O&M into a diversified infrastructure platform.
Management’s projected revenue
| Business Vertical | FY26E | FY27E | FY28E | FY29E | FY30E |
|---|---|---|---|---|---|
| Telecom & ISP | ₹1,200 Cr | ₹2,000 Cr | ₹2,500 Cr | ₹3,500 Cr | ₹3,500 Cr |
| Advanced Metering | ₹150 Cr | ₹350 Cr | ₹350 Cr | ₹350 Cr | ₹350 Cr |
| Renewable/Solar | ₹100 Cr | ₹400 Cr | ₹650 Cr | ₹1,200 Cr | ₹1,600 Cr |
| Data Centres | ₹40 Cr | ₹200 Cr | ₹400 Cr | ₹800 Cr | ₹1,200 Cr |
| Drones | ₹10 Cr | ₹50 Cr | ₹100 Cr | ₹125 Cr | ₹150 Cr |
| Total | ₹1,500 Cr | ₹3,000 Cr | ₹4,000 Cr | ₹5,975 Cr | ₹6,800 Cr |
These are management projections, not achieved financial results, and should therefore not be treated as forecasts guaranteed by the company.
Order Book & Recent Business Activity
The company has highlighted an order book exceeding ₹500 Cr in its investor materials.
A recent external validation came in July 2026 when Bondada Engineering announced a ₹10.44 Cr purchase order from Veremax for supplying BSNL 40-metre towers, foundation bolts and templates across South India.
The order is scheduled for execution within three months.
IPO / Pre-IPO Update
Veremax’s investor presentation states that the company has entered the IPO process and plans to list on stock exchanges.
It also states that:
- ₹64.50 Cr was raised through a pre-IPO transaction
- 10.35% equity was diluted
- Promoter/team holding was approximately 89.65%
- Fresh equity infusion is intended to strengthen working capital and support growth
These statements come from the company’s investor presentation and should not be interpreted as confirmation of an approved IPO timetable.
Shareholding
The company’s investor presentation indicates approximately 89.65% promoter/team ownership after the reported pre-IPO dilution, with the balance held by other investors.
Because this is an unlisted company and ownership can change through private transactions, the latest shareholding should be verified from the company’s latest statutory filing before executing a transaction.
Management
Key directors include:
- T.R.M. Venkatesh – Founder, Chairman & Managing Director
- N. Palanisamy Raja – Director
- Thulasimani Marimuthu – Director
- Sathasivam – Director
The company’s website describes Venkatesh as having more than two decades of experience in telecom, internet and IT infrastructure.
Valuation
At approximately ₹360–₹375 per share:
| Metric | Approximate |
|---|---|
| Equity Shares | ~2.22 Cr |
| Market Capitalisation | ~₹800–₹830 Cr |
| FY25 PAT | ₹61.68 Cr* |
| Indicative P/E | ~13–14x* |
| Book Value | ~₹73/share* |
| Indicative P/B | ~5x* |
*Based on the FY25 investor-presentation numbers, which are identified as unaudited, and approximate share count. Actual valuation should be recalculated using the latest audited accounts and post-issue share capital.
At first glance, the valuation looks considerably more reasonable than many high-growth unlisted technology companies.
However, valuation cannot be assessed independently of the company’s credit and liquidity issues.
The Biggest Red Flag – Credit Stress
This is the section I would prominently display on UnlistedCart.
CRISIL: Rating Downgraded to D
In March 2024, CRISIL downgraded Veremax’s corporate credit rating from CRISIL BB+/Stable to CRISIL D, citing delays in servicing term-debt obligations because of weak liquidity.
Acuité: NPA / Issuer Not Cooperating
In March 2025, Acuité downgraded one ₹45 Cr facility to ACUITE D and maintained another ₹40 Cr facility at ACUITE C, while marking the issuer “Not Cooperating.”
Acuité also stated that banker feedback indicated the account had been categorised as an NPA.
This is a significant risk factor and should not be buried in the disclaimer.
Insolvency-Related Proceedings
There is also an important NCLT development.
In September 2025, NCLT Chennai recorded proceedings initiated by Aditya Birla Capital against a personal guarantor of Veremax under Section 95 of the IBC.
The NCLT order records that Veremax had defaulted on credit facilities and that the loan account was classified as an NPA on 13 June 2025. The petition recorded an outstanding/default amount of approximately ₹16.20 Cr as of July 2025.
Importantly, the September 2025 order concerned the personal guarantor process, not an order declaring Veremax itself insolvent. The distinction should be preserved when presenting this information.
Separately, NCLT cause lists show a Section 7 petition by Aditya Birla Capital against Veremax Technologie Services Limited itself under CP(IB)/249(CHE)/2025.
Investor Takeaway
This is not a normal low-risk pre-IPO investment.
The company has demonstrated strong reported growth, but the credit history creates a major counterweight to the growth story.
Investment Positives
| Positive | Why It Matters |
|---|---|
| Strong Revenue Growth | Revenue increased from ₹325 Cr FY22 to ₹620 Cr FY25. |
| Improving Margins | EBITDA margin expanded from 2.89% to 17.04%. |
| Telecom Infrastructure Demand | 4G/5G rollout and fibre expansion create structural demand. |
| BSNL Opportunity | Government-led telecom infrastructure expansion can support order flow. |
| Diversification | Solar, smart meters, data centres and drones provide additional growth avenues. |
| Large Execution Capability | Company reports extensive fibre and tower maintenance experience. |
| IPO Potential | Management has announced an IPO process. |
| Reasonable P/E on FY25 numbers | Indicative valuation is not extremely expensive if FY25 earnings are sustainable. |
Key Risks
| Risk | Severity |
|---|---|
| Credit Stress / NPA History | 🔴 Very High |
| CRISIL D Rating | 🔴 Very High |
| Acuité D / Issuer Not Cooperating | 🔴 Very High |
| NCLT / IBC Proceedings | 🔴 Very High |
| Working Capital Intensity | 🔴 High |
| Customer Concentration | 🟠 High |
| Unlisted Liquidity | 🟠 High |
| IPO Execution Risk | 🟠 High |
| Management Projections | 🟠 High |
| Telecom Tender Dependence | 🟠 Medium–High |
| Execution of New Verticals | 🟠 Medium–High |
CRISIL specifically identified working-capital-intensive operations and customer concentration as constraints on the credit profile.
Investment View
The Bull Case
₹620 Cr revenue → telecom expansion → BSNL/4G/5G opportunity → solar + smart meters + data centres → IPO → potential valuation re-rating.
The operational growth story is genuinely interesting.
The Bear Case
High working-capital requirements → debt servicing stress → NPA/default history → expensive capital → execution pressure → IPO delays or weak valuation.
And this is not merely theoretical—the company has already faced credit-rating downgrades and NPA-related issues.
Our Assessment
| Parameter | Rating |
|---|---|
| Business Potential | ⭐⭐⭐⭐☆ |
| Revenue Growth | ⭐⭐⭐⭐⭐ |
| Margin Expansion | ⭐⭐⭐⭐⭐ |
| Industry Opportunity | ⭐⭐⭐⭐☆ |
| Diversification | ⭐⭐⭐⭐☆ |
| Balance Sheet Quality | ⭐⭐☆☆☆ |
| Credit Profile | ⭐☆☆☆☆ |
| IPO Potential | ⭐⭐⭐⭐☆ |
| Valuation | ⭐⭐⭐⭐☆ |
| Liquidity | ⭐⭐☆☆☆ |
| Overall Risk | VERY HIGH |
Investment Takeaway
Veremax is an interesting business with a very important risk attached to it.
The operating story is strong:
Telecom + 4G/5G + Fibre + BSNL + Solar + Smart Meters + Data Centres + Drones.
But the financial-risk story is equally important:
Credit stress + NPA classification + CRISIL D + Acuité D + IBC-related proceedings.
Therefore, I would not position Veremax on UnlistedCart simply as a “high-growth telecom pre-IPO stock.”
A more accurate positioning would be:
“High-Growth Telecom Infrastructure Pre-IPO — High Financial & Credit Risk”
The potential upside comes from business growth and a successful IPO, while the principal downside risk comes from debt servicing, working capital, liquidity and the company’s ability to resolve its credit stress.
How to Invest
Veremax Technologie Services Limited is currently unlisted and its shares are traded through the unlisted/off-market market rather than normal NSE/BSE trading.
Indicative market prices around ₹360–₹375 have been reported in September 2026, but actual executable prices can vary significantly based on quantity, seller availability and transaction terms.
Before investing, investors should specifically verify:
- Latest audited FY26 financials
- Current debt outstanding
- Status of all NPA/default accounts
- Current status of NCLT proceedings
- Latest credit ratings
- IPO/DRHP status
- Latest shareholding
- Exact post-pre-IPO share capital
- Current executable unlisted price
- Any additional promoter pledges/encumbrances
Final Verdict
Veremax is a potentially high-growth infrastructure story—but it is NOT a low-risk pre-IPO investment.
The company has demonstrated impressive revenue and EBITDA growth, but the credit-rating history and insolvency-related proceedings materially increase the risk profile.
For an aggressive investor: Potentially interesting at the right valuation.
For a conservative investor: Avoid until credit stress is demonstrably resolved.
For UnlistedCart: Best classified under “High-Risk Pre-IPO / Special Situation.”
Official company website: Veremax Technologie
Disclaimer
This profile is for informational and educational purposes only and does not constitute investment advice or a recommendation to buy or sell securities. Veremax Technologie Services Limited is an unlisted security with significant liquidity, credit, execution, valuation and IPO-related risks. FY25 financial figures cited from the investor presentation are identified as unaudited. Investors should independently verify the latest audited financial statements, debt position, rating status, NCLT proceedings, shareholding and IPO documents before investing.
For more such unlisited stocks visit https://unlistedcart.com/unlisted-shares/
