Holistic House International Ltd. — Impresso Foods
Unlisted Company Research Report
CIN: U15549MH2018PLC316130
Former name: Holistic House International Private Limited
Incorporated: 23 October 2018
Status: Active, Unlisted Public Company
Registered Office: Panvel, Maharashtra
Brand: Impresso Foods
Industry: FMCG / Food & Beverages
ISIN: INE0QY401013 (ZaubaCorp)
1. Company Overview
Holistic House International Ltd. is an Indian food and FMCG company operating primarily through its Impresso Foods brand.
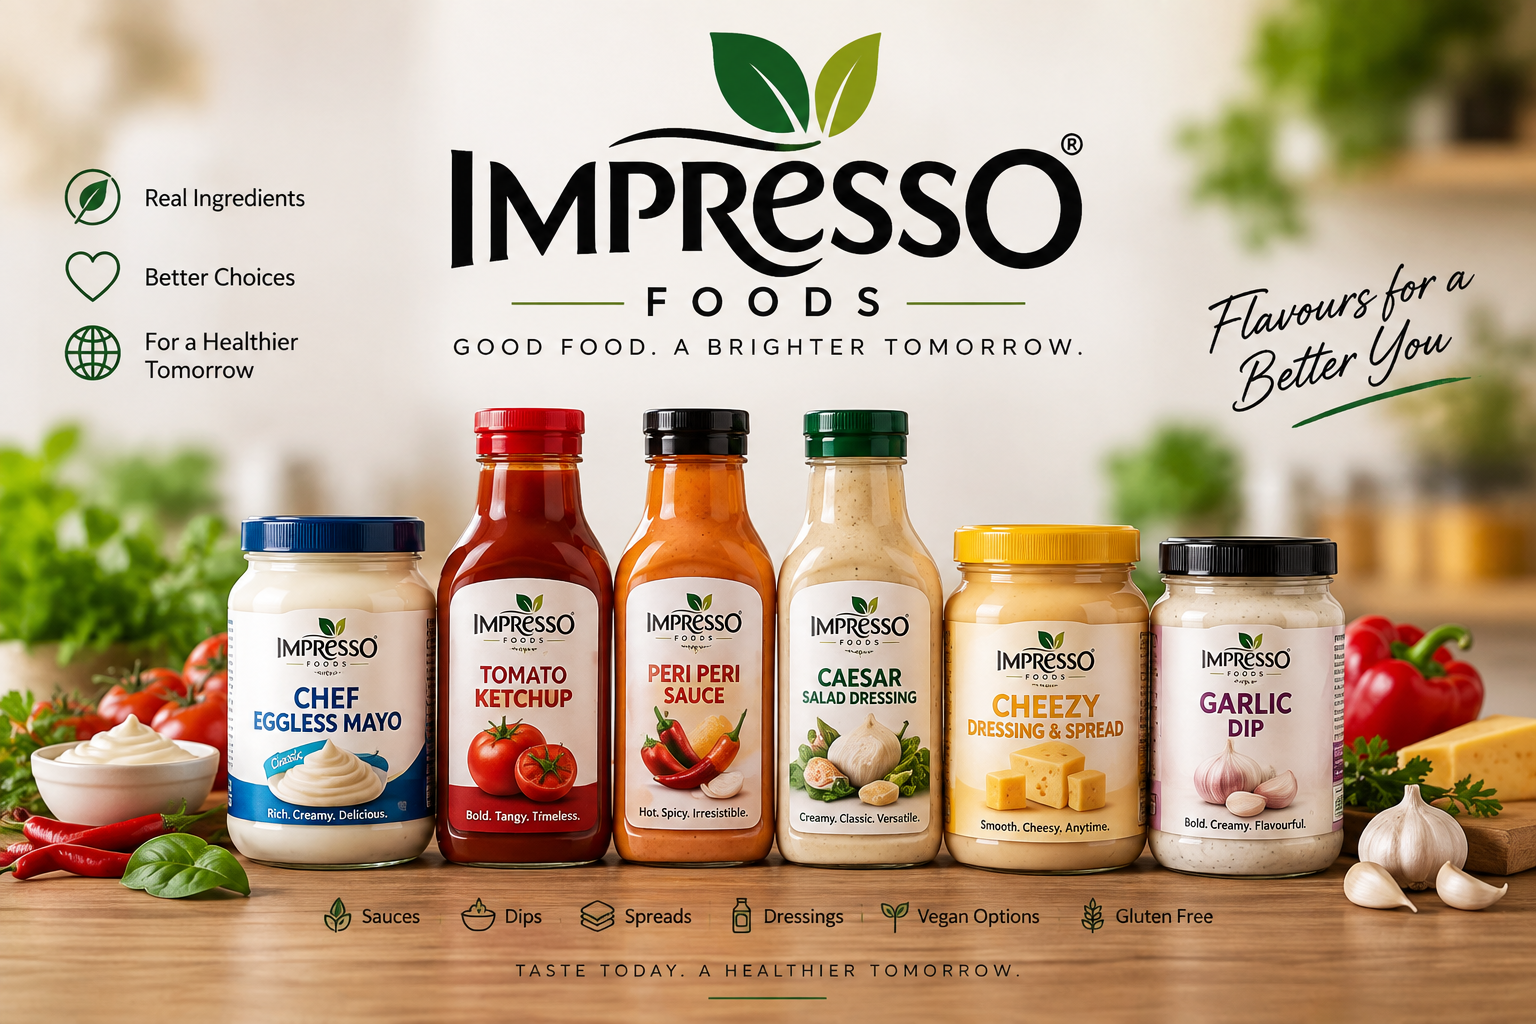
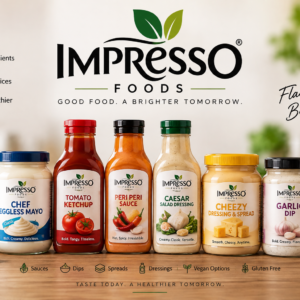
The company focuses on condiments, sauces, mayonnaise, dips, spreads, dressings and related food products. Its official website describes Impresso as a brand built around sauces, dips and spreads, with an emphasis on quality, affordability and product innovation. (Impresso Foods)
The company says the business is backed by 30+ years of experience in the food industry through the promoter/management team’s experience. It also has a strategic partnership with Impresoo Foods LLC, Delaware, USA, for marketing and distribution of its Made-in-India products in international markets including the Indian subcontinent, GCC countries and Africa. (Impresso Foods)
2. What does Impresso Foods sell?
The company’s product portfolio includes:
- Mayonnaise
- Dips
- Sauces
- Salad dressings
- Spreads
- Mustard
- Toppings
- Vegan products
- Gluten-free products
- Horeca-focused products
Its online store currently lists products such as Caesar Salad Dressing & Marinade, Cheezy Dressing & Spread and Chef Eggless Mayo, among others. (Impresso Foods)
This gives the company exposure to both:
B2C FMCG consumption
and
B2B / HoReCa demand.
3. Business Model
The opportunity here is essentially a branded-food business.
Rather than competing purely as a commodity food manufacturer, Impresso is trying to establish a consumer brand in categories where consumers increasingly buy packaged sauces, mayonnaise, dips and dressings.
The company’s stated vision is to establish Impresso in everyday consumer usage, particularly across condiments, spreads and sauces. (Impresso Foods)
This is important because branded FMCG businesses can potentially command better economics than purely contract-manufacturing businesses if they successfully build:
Brand → Distribution → Repeat purchase → Scale → Margin expansion.
4. Manufacturing & Operations
The company’s official website identifies its factory at:
Zurange Warehouse, GAT 1150, Ward 02, Saswadjejurird, Khalad, Purandar–Saswad, Maharashtra.
Its sales and marketing office is located in Pune. (Impresso Foods)
The company says its products are manufactured using advanced technologies and that it has an emphasis on R&D and product innovation. (Impresso Foods)
5. International Opportunity
One of the more interesting aspects of the company is its international strategy.
Holistic House states that it has a long-term strategic partnership with Impresoo Foods LLC in Delaware, USA, for joint marketing and distribution.
The target international markets mentioned by the company include:
- Indian subcontinent
- GCC
- Africa
This potentially provides a route for an Indian FMCG brand to expand beyond the domestic market. (Impresso Foods)
However, investors should distinguish between international presence/partnership and actual material export revenue. The latter needs to be verified from the audited financial statements.
6. Financial Position — Important ⚠️
This is where I would be particularly careful with Holistic House.
Public databases currently provide inconsistent financial information.
TheCompanyCheck reports FY25 revenue of approximately ₹5.11 lakh, down 44% YoY. (The Company Check)
At the same time, Tofler reports FY25 financial metrics but hides the absolute revenue/profit numbers behind its paid report. It indicates:
- Revenue: below ₹1 crore
- Revenue change: -43.99%
- Net worth change: -14.77%
- Borrowings change: +52.09%
- Assets change: +2.14%
- Debt/equity: 0.28x
- ROE: -9.41%
- ROCE: -4.82% (Tofler)
This is a major red flag for the investment analysis.
The company’s brand presence appears considerably larger than the revenue figures currently visible in public corporate databases.
Therefore, before publishing a financial-performance table on UnlistedCart, I would strongly recommend obtaining the actual FY2024-25 audited financial statements/AOC-4 attachment.
I would not present ₹5.11 lakh as the company’s definitive operational revenue without reconciling it with the audited filing, because it appears unusually small for a company that has an established FMCG brand, factory operations, online sales and stated international distribution ambitions.
7. Capital Structure
According to current corporate records:
| Particular | Details |
|---|---|
| Authorised Capital | ₹10 crore |
| Paid-up Capital | ₹9.61 crore |
| Status | Unlisted |
| Company Type | Public Limited |
| Incorporation | 2018 |
ZaubaCorp reports paid-up capital of approximately ₹9.61 crore against authorised capital of ₹10 crore. (ZaubaCorp)
This is important when looking at the current unlisted share price because the company has a relatively large number of shares outstanding.
Moneycontrol currently reports approximately 96.08 million shares outstanding and an indicative unlisted price around ₹36.97, implying a market capitalization of roughly ₹355–356 crore, although its displayed market-cap figure is ₹383.63 crore and its data should be treated as indicative. (Moneycontrol)
8. Current Unlisted Valuation
This is where I would be very cautious.
Moneycontrol currently displays:
Indicative price: ₹36.97
52-week range: ₹35.75–₹50
Book value: ₹0.33
P/B: 120.23x
P/E: Not available
P/S: Not available (Moneycontrol)
The extremely high reported P/B ratio is a consequence of the very low reported book value and should not automatically be interpreted as proof that the company is overpriced.
But it does tell us something important:
At the current unlisted price, the investment thesis cannot be based on existing book value.
The investor is effectively paying for future growth and brand potential.
9. Growth Strategy
The company’s growth strategy appears to be built around:
Product expansion
The company has continued introducing products across sauces, dips, spreads, dressings and mayonnaise.
Planify reports that the company launched 10 new products in FY24 and had moved around 70% of its product packaging to eco-friendly materials. It also reports a management target of reaching ₹500 crore revenue by 2030. (Planify)
Distribution expansion
The company aims to increase its presence across consumer and institutional channels.
International expansion
The Impresoo Foods partnership provides a potential route into GCC, Africa and other international markets. (Impresso Foods)
Brand building
The longer-term objective is to turn Impresso into an everyday-use FMCG brand rather than simply remain a small food manufacturer.
10. Competitive Opportunity
The Indian packaged-food market has several large established players.
Impresso operates in categories where consumers are already familiar with brands in:
- Mayonnaise
- Ketchup
- Sauces
- Dressings
- Dips
- Spreads
Therefore, the company has a large addressable market, but also faces strong competition.
The key question isn’t whether the market is large.
It is:
Can Impresso acquire consumers and distribution at a cost that allows it to become profitable at scale?
That is the critical investment question.
11. Key Strengths
✅ 1. Consumer-facing FMCG brand
Impresso gives the company a recognizable consumer proposition rather than being purely a B2B manufacturer.
✅ 2. Large addressable market
Sauces, mayonnaise, spreads, dips and dressings are recurring-consumption categories.
✅ 3. Product innovation
The company has continued expanding its product portfolio. (Impresso Foods)
✅ 4. International potential
The strategic partnership with Impresoo Foods LLC provides a potential international distribution channel. (Impresso Foods)
✅ 5. Experienced management
The company states that the business benefits from more than 30 years of food-industry experience. (Impresso Foods)
✅ 6. Unlisted early-stage opportunity
If the company successfully scales its brand and distribution, an early investor could potentially benefit from substantial growth before any future listing.
12. Key Risks
⚠️ 1. Financial transparency
Current publicly available databases do not provide a clean, consistent picture of the company’s financial performance.
⚠️ 2. Profitability
Available FY25 indicators from Tofler suggest negative ROE and ROCE, which indicates that the business needs to demonstrate stronger profitability. (Tofler)
⚠️ 3. High valuation expectations
At an indicative price around ₹37, the company is valued substantially above its reported book value. (Moneycontrol)
⚠️ 4. Competition
The FMCG condiment market is highly competitive and includes established domestic and multinational brands.
⚠️ 5. Execution risk
The stated goal of ₹500 crore revenue by 2030 represents a very significant scale-up from the currently reported financial base. (Planify)
⚠️ 6. Liquidity
Like other unlisted companies, there is no regular NSE/BSE market through which investors can freely buy or sell the shares.
13. Overall Investment View
Holistic House / Impresso Foods: HIGH-GROWTH POTENTIAL, HIGH EXECUTION RISK
I would not position this as a fundamentally proven FMCG company yet.
The interesting part of the story is the combination of:
FMCG + branded products + product innovation + distribution expansion + international opportunity.
But the biggest question is:
Can the company convert the brand opportunity into meaningful revenue and sustainable profitability?
Currently available financial information does not yet give enough comfort to answer that confidently.
My rating framework
| Factor | Assessment |
|---|---|
| Industry opportunity | 🟢 Strong |
| Brand opportunity | 🟢 Interesting |
| Product portfolio | 🟢 Positive |
| International opportunity | 🟢 Positive |
| Management experience | 🟢 Positive |
| Revenue visibility | 🟡 Needs verification |
| Profitability | 🔴 Weak / unclear |
| Valuation | 🔴 Aggressive |
| Liquidity | 🔴 High risk |
| Overall | 🟡 High-risk growth opportunity |
Impresso Foods official website
For more such unlisted stocks visit https://unlistedcart.com/unlisted-shares/
Reviews
There are no reviews yet.